Australia from Asia: macro & credit-cycle dashboard
Last updated: 13 Oct 2026, 15:07 AWST (Perth). Built from free public data. Australia's cycle viewed through a triangle of China (commodities, terms of trade, property-credit), Japan (rates, yen, capital flows) and the US (Fed, Treasuries, dollar funding), linked by the global credit cycle. Every traffic light comes from the explicit rule printed on its card.
HEATING running hot / accelerating / tightening pressure building (e.g. inflation above target, rapid credit growth, rising yields, booming asset prices)
STEADY inside its normal range under the stated rule
COOLING slowing / weakening, or a restrictive setting that is exerting cooling pressure (e.g. high real rates, inverted curve)
STRESS dislocation signal: spreads or insolvencies surging, carry unwind, sharp drawdown, labour-market break (Sahm-style)
INFO context chart only, no traffic-light rule
Traffic-light summary
27heating 59steady 16cooling 5stress
| Indicator | Latest | Date | Change | Status | Rule result |
|---|---|---|---|---|---|
| Australia heating 10 · steady 23 · cooling 9 · stress 2 | |||||
| Unemployment rate | 4.6% | Aug 2026 | +0.4pp over 1y | COOLING | 3-mo avg 4.50%: +0.33pp vs prior-12m low, +0.23pp y/y |
| Underemployment & underutilisation | 6.2% | Aug 2026 | +0.5pp over 1y | COOLING | underemployment +0.5pp y/y |
| Youth (15-24) unemployment rate | 10.8% | Aug 2026 | +1.1pp over 1y | COOLING | +1.1pp y/y |
| Hours worked & employment growth (y/y) | 1.0% | Aug 2026 | -0.3pp over 1y | STEADY | trend hours +1.0% y/y |
| Employment-to-population ratio | 63.9% | Aug 2026 | -0.1pp over 1y | STEADY | -0.1pp y/y |
| Job vacancies ('000) | 325 '000 | Q3 2026 | -1.4% over 1y | STEADY | -1.4% y/y; vacancies/labour force 2.1% |
| Wage Price Index (y/y) | 3.2% | Q2 2026 | -0.2pp over 1y | STEADY | 3.2% y/y |
| Unit labour costs & productivity (y/y) | 3.5% | Q2 2026 | -1.2pp over 1y | STEADY | ULC 3.5% y/y; productivity -0.3% |
| Trimmed mean CPI (y/y) | 3.6% | Aug 2026 | +0.1pp over 3m | HEATING | monthly trimmed mean 3.6% y/y (quarterly 3.6% to Jun 2026) |
| Headline CPI (y/y) | 4.0% | Aug 2026 | +0.0pp over 3m | HEATING | 4.0% y/y |
| Services vs goods inflation (y/y) | 3.7% | Aug 2026 | +0.0pp over 3m | STEADY | services 3.7%, goods 4.2% y/y |
| Rents, insurance & electricity (y/y) | 3.6% | Aug 2026 | +0.0pp over 3m | STEADY | rents 3.6%, insurance 5.6%, electricity 13.2% y/y |
| Consumer inflation expectations (1y ahead) | 4.9% | Q3 2026 | +0.2pp over 1y | STEADY | 4.9% |
| Cash rate & real cash rate | Cash 4.60% (12 Oct 2026) | Aug 2026 | +0.2pp over 1y | STEADY | cash 4.60% minus trimmed mean = +0.75pp |
| AGS 3y & 10y yields | 4.93% | 07 Oct 2026 | +51bp over 3m | HEATING | 3y 4.93% (+51bp 3m); 10y 5.40%; 10y-3y +47bp |
| AGS 10y-3y curve | +0.47 pp | 07 Oct 2026 | +4bp over 3m | STEADY | +47bp |
| AGS indexed bond (real) yield | 3.00% | 07 Oct 2026 | +48bp over 3m | COOLING | 3.00% |
| 3m BBSW minus cash rate (funding proxy) | +0.17 pp | 12 Oct 2026 | +5bp over 3m | STEADY | +17bp |
| BBB corporate spread to AGS (5y) | 1.09 pp | Aug 2026 | +14bp over 3m | HEATING | spread at 8th percentile of trailing 10 years |
| Housing credit growth (y/y) | 7.3% | Aug 2026 | +1.2pp over 1y | COOLING | y/y 7.3%, 3-mo annualised 6.2% (-1.1pp vs y/y) |
| Investor housing credit growth (y/y) | 9.6% | Aug 2026 | +2.6pp over 1y | COOLING | y/y 9.6%, 3-mo annualised 6.2% (-3.4pp vs y/y) |
| Business credit growth (y/y) | 10.9% | Aug 2026 | +1.1pp over 1y | HEATING | y/y 10.9%, 3-mo annualised 12.7% (+1.8pp vs y/y) |
| Mortgage rates (variable) | 6.20% | Aug 2026 | +70bp over 1y | STEADY | outstanding OO variable 6.20% minus trimmed mean = +2.60pp (Aug 2026) |
| New housing loan commitments (A$bn/qtr) | 97.6 A$bn | Q2 2026 | +6.8% over 1y | STEADY | +6.8% y/y; investor +8.1% |
| Non-ADI (non-bank) share of new housing loans | 10.7% | Q2 2026 | +3.8pp over 1y | HEATING | 10.7% (+3.8pp y/y) |
| Mean dwelling price (y/y) | 6.8% | Q2 2026 | -3.2pp over 3m | STEADY | +6.8% y/y; mean price A$1,100k |
| Private dwelling approvals ('000/month) | 17.9 '000 | Aug 2026 | +4.7% over 6m | STEADY | trend +4.7% over 6m |
| Dwelling commencements & completions ('000, 4-qtr sum) | 204 '000 | Q2 2026 | +13.2% over 1y | HEATING | commencements 204k (+13.2% y/y); completions 180k; under construction 248k |
| Household spending (nominal, y/y) | 6.8% | Aug 2026 | +2.1pp over 1y | STEADY | nominal 6.8%, approx real +2.8% (Aug 2026); discretionary 7.2% |
| Household saving ratio | 6.5% | Q2 2026 | +0.6pp over 1y | STEADY | 6.5% (+0.6pp y/y) |
| Real GDP & GDP per capita (y/y) | 0.7% | Q2 2026 | +0.3pp over 1y | STEADY | per capita +0.7%, total +2.1% y/y |
| NAB business conditions | -4.2 net bal. | Aug 2026 | -3.7 over 3m | COOLING | -4.2 |
| Westpac-MI consumer sentiment | 80.4 | Oct 2026 | -3.5 over 3m | COOLING | 80.4 |
| Companies entering external administration (ASIC Series 1) | 1808 count/mo | Aug 2026 | 3-mo sum +16% y/y | COOLING | 3-mo sum 4355 (+16% y/y); construction 3-mo 1457 (+54% y/y) |
| Terms of trade (index) | 94.8 | Q2 2026 | -0.5% over 1y | STEADY | -0.5% y/y |
| RBA commodity price index | 106.6 | Sep 2026 | +6.6% over 1y | STEADY | A$ +6.6% y/y; US$ +15.2% |
| Iron ore (US$/t) | 98 US$ | Sep 2026 | -5.4% over 1y | STEADY | -5.4% y/y |
| Thermal coal, Newcastle (US$/t) | 147 US$ | Sep 2026 | +38.4% over 1y | HEATING | +38.4% y/y |
| LNG, Japan import price (US$/mmbtu) | 14.25 US$ | Sep 2026 | +24.2% over 1y | HEATING | +24.2% y/y |
| Gold (US$/oz) | 4,319 US$ | Sep 2026 | +17.7% over 1y | HEATING | +17.7% y/y |
| AUD: US$ and trade-weighted index | 0.6961 US$ | 13 Oct 2026 | -0.5% over 3m | STEADY | AUD/USD 0.6961; TWI 64.7 (-1.1% 3m) |
| Listed private-credit trusts: price vs NTA | 1.645 A$ | 13 Oct 2026 | -6.0% over 1m | STRESS | MXT 1.645 vs NTA 1.962 (-16.1%); MOT 1.495 vs NTA 1.935 (-22.7%); MRE 1.410 vs NTA 2.22 (-36.5%) |
| ASX 200 and financials | 8,784 | 13 Oct 2026 | -0.6% over 3m | STEADY | -5.3% vs 52-week high |
| ASX 200 A-REITs | 3,236 | 13 Oct 2026 | -8.8% over 3m | STRESS | -23.6% vs 52-week high |
| RBA Chart Pack highlights heating 0 · steady 2 · cooling 2 · stress 0 | |||||
| Housing loan payments to disposable income | 9.4% | Q1 2026 | -0.5pp over 1y | COOLING | 9.4% vs 10y avg 8.3% |
| Broad money and M1 growth (y/y) | 6.9% | Aug 2026 | +0.1pp over 1y | STEADY | broad money 6.9%, M1 6.5% y/y |
| Real wage growth (WPI minus CPI, y/y) | -0.7 pp | Q2 2026 | -2.0pp over 1y | COOLING | WPI 3.2% minus CPI 3.9% |
| Longer-term inflation expectations | 2.5% | Q3 2026 | -0.1pp over 1y | STEADY | economists 2.5%, 10y break-even 2.4% |
| China heating 2 · steady 7 · cooling 1 · stress 2 | |||||
| Credit impulse (BIS, % of GDP) | 0.9 % GDP | Q1 2026 | +1.6pp over 1y | STEADY | total non-fin +0.9pp; private -1.1pp of GDP |
| NBS manufacturing PMI | 50.1 | Sep 2026 | -0.2 over 3m | STEADY | 50.1 |
| NBS non-manufacturing PMI | 50.2 | Sep 2026 | +0.0 over 3m | STEADY | 50.2 |
| CPI (y/y) | 0.8% | Aug 2026 | -0.4pp over 3m | STEADY | +0.8% y/y |
| Producer prices (y/y) | 3.8% | Aug 2026 | -0.1pp over 3m | HEATING | +3.8% y/y |
| Industrial production & retail sales (y/y) | 5.2% | Aug 2026 | +0.7pp over 3m | STEADY | IP +5.2%, retail sales +0.4% y/y |
| Property: starts, sales & investment (YTD y/y) | -24.8% | Aug 2026 | -2.2pp over 3m | STRESS | starts -24.8%, sales -13.0%, investment -19.9% YTD y/y |
| 70-city new home prices (avg y/y) | -3.3% | Aug 2026 | +0.4pp over 3m | STRESS | -3.3% y/y; -0.17% m/m; 48 of 70 cities falling m/m |
| Exports (US$, 3-mo y/y) | 25.2% | Aug 2026 | +13.3pp over 3m | HEATING | 3-mo exports +25.2% y/y |
| China 10y government bond yield | 1.69% | Aug 2026 | -15bp over 1y | STEADY | 1.69% (-15bp y/y) |
| USD/CNY | 6.6959 CNY | 13 Oct 2026 | -1.1% over 3m | STEADY | 6.6959 (-1.1% 3m) |
| Shanghai Composite & Hang Seng China Enterprises | 8,169 | 13 Oct 2026 | -1.8% over 3m | COOLING | -14.9% vs 52-week high |
| Japan heating 2 · steady 7 · cooling 0 · stress 1 | |||||
| BoJ policy rate | 1.25% | 06 Oct 2026 | +0.8pp over 1y | HEATING | 1.25% (+0.75pp y/y) |
| JGB 2y & 10y yields | 3.027% | 09 Oct 2026 | +27bp over 3m | HEATING | 10y 3.027% (+27bp 3m); 2y 1.911% |
| JGB 30y yield | 4.085% | 09 Oct 2026 | +15bp over 3m | STEADY | 4.085% (+6bp 1m, +15bp 3m) |
| USD/JPY | 158.27 JPY | 13 Oct 2026 | +2.0% over 1m | STEADY | 158.27 (+2.0% 1m, -2.4% 3m) |
| AUD/JPY | 110.17 JPY | 13 Oct 2026 | -0.5% over 1m | STEADY | 110.17 (-0.5% 1m, -2.9% 3m) |
| Japan CPI (y/y) | 1.9% | Jul 2026 | +0.6pp over 3m | STEADY | 1.9% y/y |
| Japanese net buying of foreign bonds (13-wk sum, ¥tn) | -1.8 ¥tn | 03 Oct 2026 | latest week -0.35tn | STEADY | -1.8tn over 13 wks (22th pct) |
| Foreign net buying of Japanese equities & bonds (13-wk, ¥tn) | -3.2 ¥tn | 03 Oct 2026 | latest week equities +2.19tn | STRESS | equities -3.2tn, long-term debt +0.8tn over 13 wks (9th pct) |
| Nikkei 225 | 67,702 | 13 Oct 2026 | +1.3% over 3m | STEADY | -6.4% vs 52-week high |
| Japan exports (US$, 3-mo y/y) | 9.8% | Aug 2026 | +4.6pp over 3m | STEADY | 3-mo exports +9.8% y/y |
| US & global credit heating 7 · steady 12 · cooling 3 · stress 0 | |||||
| Fed funds & real fed funds | FF 3.88%, real +0.62pp | Aug 2026 | -0.9pp over 1y | STEADY | effective 3.88% (08 Oct); real +0.62pp (Aug 2026); +24bp over 6m |
| US Treasury 2y & 10y | 5.22% | 08 Oct 2026 | +66bp over 3m | HEATING | 10y 5.22% (+66bp 3m); 2y 4.75% |
| US 2s10s curve (10y minus 2y) | +0.44 pp | 09 Oct 2026 | +9bp over 3m | STEADY | +44bp |
| US 10y real yield (TIPS) & breakeven | 2.87% | 08 Oct 2026 | +55bp over 3m | COOLING | real 2.87%, breakeven 2.33% |
| Broad trade-weighted US dollar | 121.4 | 02 Oct 2026 | +0.6% over 3m | STEADY | +0.6% 3m, +0.8% 12m |
| SOFR minus IORB (repo funding pressure, bp) | -3 bp | 08 Oct 2026 | +7bp over 3m | STEADY | latest -3bp, 5-day avg -1.6bp; ON RRP US$0bn |
| US high-yield & IG corporate spreads (OAS) | 3.15% | 08 Oct 2026 | +46bp over 3m | HEATING | HY 3.15%, IG 0.82% (HY at 62th pct of available history) |
| Asia USD corporate & EM high-yield spreads | 0.91% | 08 Oct 2026 | +10bp over 3m | STEADY | Asia corp OAS at 34th percentile of trailing 10 years |
| BDC index ETF (BIZD): listed US private-credit proxy | 12.10 US$ | 12 Oct 2026 | -4.5% over 3m | COOLING | -19.6% vs 52-week high |
| Chicago Fed NFCI & St Louis stress index | -0.49 | 02 Oct 2026 | +0.0 over 3m | HEATING | NFCI -0.49; STLFSI -0.47 |
| VIX | 14.8 | 09 Oct 2026 | -1.0 over 1m | STEADY | 14.8 |
| US banks tightening C&I lending standards (net %) | +0.0 net % | Q3 2026 | -9.5 over 1y | STEADY | +0.0 net % tightening |
| US bank C&I loans (y/y) | 10.0% | Sep 2026 | +13.1pp over 1y | COOLING | y/y 10.0%, 3-mo annualised 8.8% (-1.2pp vs y/y) |
| US core PCE & CPI inflation (y/y) | 3.0% | Aug 2026 | -0.2pp over 3m | HEATING | core PCE 3.0%, CPI 3.7% |
| US unemployment rate & Sahm rule | 4.2% | Sep 2026 | -0.2pp over 1y | STEADY | 3-mo avg 4.13%: +0.00pp vs prior-12m low, -0.10pp y/y; FRED SAHMREALTIME 0.00 |
| US initial jobless claims (4-wk avg, '000) | 198 '000 | 03 Oct 2026 | -15.4% over 1y | HEATING | 198k (-15.4% y/y) |
| Fed balance sheet (US$tn) | 6.75 US$tn | 07 Oct 2026 | +2.4% over 1y | STEADY | US$6.75tn (+2.4% y/y) |
| Brent crude (US$/bbl) | 125.4 US$ | 06 Oct 2026 | +87.0% over 1y | HEATING | US$125.4 (+87.0% y/y) |
| USD credit to non-banks outside the US (y/y) | 7.3% | Q1 2026 | +2.1pp over 1y | STEADY | +7.3% y/y |
| Credit-to-GDP gaps (BIS, pp) | -9.7 pp | Q1 2026 | +3.8pp over 1y | HEATING | Japan +5.7; China -5.1; Australia -9.7; US -11.3; Korea -15.1; Euro area -17.1 (highest: Japan) |
| Private-sector debt service ratios (BIS, % of income) | 20.3% | Q1 2026 | -0.3pp over 1y | STEADY | AU 20.3% vs 10y avg 19.5%; China 19.1, Japan 15.5, US 13.8, Korea 19.3 |
| Private credit impulse (BIS, % of GDP) | 0.2 % GDP | Q1 2026 | -2.2 over 1y | STEADY | Australia +0.2, US +2.8, Japan +7.0, Korea +0.2 |
| Funding & liquidity heating 2 · steady 6 · cooling 0 · stress 0 | |||||
| Repo vs IORB: SOFR, TGCR and SOFR 99th percentile (bp) | -3 bp | 08 Oct 2026 | +7bp over 3m | STEADY | SOFR 3.87%, TGCR 3.85%, BGCR 3.85%; SOFR-IORB 5d -1.6bp, p99 5d +6.4bp |
| Primary dealer Treasury fails (deliver + receive, ex-TIPS, US$bn/week) | 260.0 US$bn | 30 Sep 2026 | -18.8% over 1y | HEATING | fails to deliver US$130.7bn + receive US$129.3bn (wk 30 Sep); 4-wk avg 1.7x the 3-yr median |
| Fed overnight repo operations incl. Standing Repo Facility (US$bn/day) | 0.0 US$bn | 09 Oct 2026 | +0.0 over 3m | STEADY | latest US$0.0bn; 20-day max US$1.2bn (30 Sep); H.4.1 repo (Wed) US$0.0bn |
| Fed central bank liquidity swaps outstanding (US$bn) | 0.21 US$bn | 07 Oct 2026 | +0.2 over 1y | STEADY | US$207m outstanding (peaks: US$583bn Dec-2008, US$449bn May-2020) |
| Discount window: primary & secondary credit (US$bn) | 9.96 US$bn | 07 Oct 2026 | +2.8 over 1y | HEATING | primary US$9.96bn (3-yr median 4.69bn); secondary US$0m |
| Near-term forward spread: 3m rate 18m ahead minus 3m bill (bp) | +97 bp | 02 Oct 2026 | +66bp over 3m | STEADY | +97bp (02 Oct); 18m-ahead 3m forward 5.16% |
| US Treasury curve: 10y-3m and 10y-2y (pp) | +0.99 pp | 09 Oct 2026 | +28bp over 3m | STEADY | 10y-3m +0.99pp, 10y-2y +0.44pp (09 Oct) |
| Copper/gold ratio (x1000) vs US 10y yield | 1.60 ratio | 13 Oct 2026 | +30.0% over 1y | STEADY | 1.60 (copper US$6.76/lb, gold US$4,216/oz); +3.1% over 3m |
| Asia region heating 4 · steady 2 · cooling 1 · stress 0 | |||||
| Korea exports (US$, 3-mo y/y) | 67.5% | Aug 2026 | +17.1pp over 3m | HEATING | 3-mo exports +67.5% y/y |
| Asia-5 exports (US$, 3-mo y/y) | 27.1% | Aug 2026 | +12.3pp over 3m | HEATING | 3-mo exports +27.1% y/y |
| TAIEX & KOSPI (semiconductor cycle proxy) | 48,341 | 13 Oct 2026 | +79.6% over 1y | HEATING | TAIEX +80% 12m (-3.0% vs 52w high); KOSPI +67% 12m |
| OECD business confidence (PMI substitute) | 99.81 | Aug 2026 | +0.0 over 3m | STEADY | CN/JP/KR avg 99.81; China 98.4 (Aug), Japan 101.7 (Sep), Korea 99.4 (Sep), Australia 99.9 (Aug), US 100.3 (Sep), Indonesia 99.0 (Jun) |
| Asian FX basket vs USD (8 currencies, equal weight) | 95.6 | 13 Oct 2026 | +1.3% over 3m | STEADY | +1.3% 3m; worst 3m: KRW +10.9%, TWD -0.1%, INR +0.6%, IDR +1.3%, SGD +1.1%, THB -0.6%, MYR -0.1%, PHP -2.0% |
| Policy rates: Korea, India, Indonesia, China + AU, JP, US | 3.00% | 28 Aug 2026 | +50bp over 6m | HEATING | 6m: cut none; hiked KR, ID, JP, AU, US; KR 3.00, IN 5.25, ID 5.75, CN 3.00, JP 1.25, AU 4.60, US 3.88 |
| Hang Seng Index | 24,295 | 13 Oct 2026 | -2.9% over 3m | COOLING | -13.1% vs 52-week high |
Australia
10heating 23steady 9cooling 2stress
Labour market
Unemployment rateCOOLING
4.6% +0.4pp over 1y
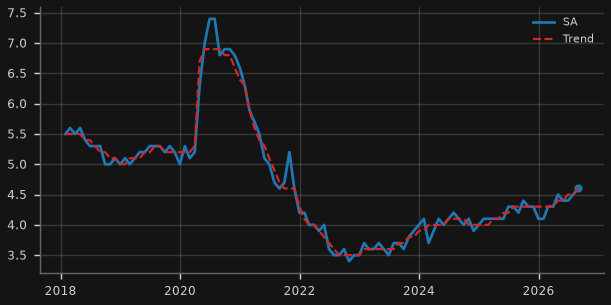
Why it matters for Australia: The single best real-time read on whether high real rates are cracking household cash flow (and mortgage arrears).
Rule: Stress if 3-mo avg >= 0.5pp above its low of the prior 12 months (Sahm-style); else cooling if 3-mo avg up >= 0.2pp y/y; heating if down >= 0.2pp y/y; otherwise steady.
Source: RBA table H5: GLFSURSA, GLFSURTR
6.2% +0.5pp over 1y
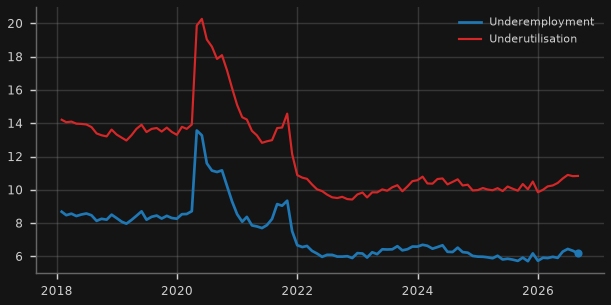
Why it matters for Australia: Spare capacity beyond the headline rate: hours slack shows up before job losses.
Rule: Cooling if underemployment rate up >= 0.3pp y/y; heating if down >= 0.3pp; otherwise steady.
Source: ABS Data API (LF_UNDER,1.0.1): M23+M24.3.1599.20.AUS.M
10.8% +1.1pp over 1y
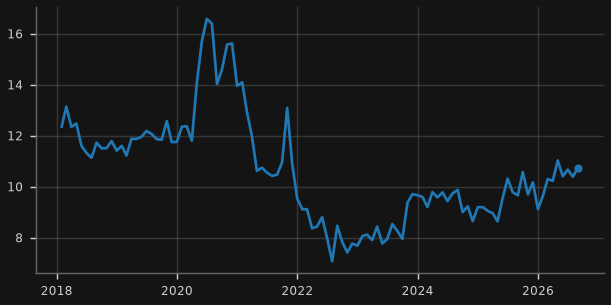
Why it matters for Australia: Youth jobs are the marginal hire: they turn first when firms freeze hiring.
Rule: Cooling if up >= 1pp y/y; heating if down >= 1pp y/y; otherwise steady.
Caveat: Noisy monthly series (small sample).
Source: ABS Data API (LF_UNDER,1.0.1): M13.3.1524.20.AUS.M
1.0% -0.3pp over 1y
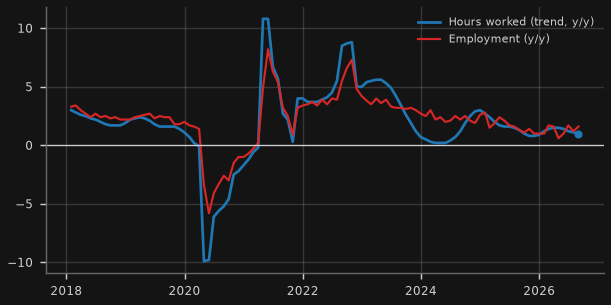
Why it matters for Australia: Hours are the volume of labour actually used; falling hours with steady jobs is an early slowdown sign.
Rule: Trend hours y/y: heating > 2.5%; cooling < 0.5%; otherwise steady.
Source: RBA table H5: GLFMHWTRYP, GLFSEPTSYP
63.9% -0.1pp over 1y
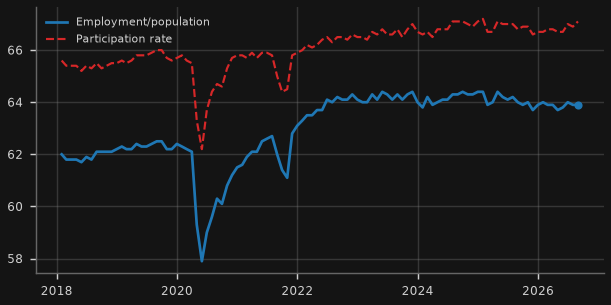
Why it matters for Australia: Captures jobs relative to a fast-growing population (avoids flattering by migration).
Rule: Cooling if down >= 0.3pp y/y; heating if up >= 0.3pp y/y; otherwise steady.
Source: RBA table H5: GLFSEPTPOP, GLFSPRSA
Job vacancies ('000)STEADY
325 '000 -1.4% over 1y
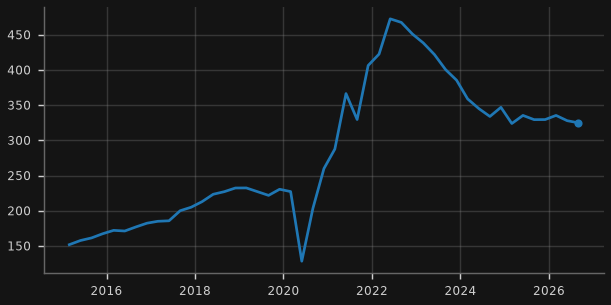
Why it matters for Australia: Labour demand: vacancies fall before unemployment rises.
Rule: Vacancies y/y: heating > +10%; cooling < -10%; otherwise steady.
Caveat: ABS Job Vacancies survey; quarterly, dated to the middle month of the quarter.
Source: RBA table H5: GLFOSVT, GLFOSVTLF
Wage Price Index (y/y)STEADY
3.2% -0.2pp over 1y
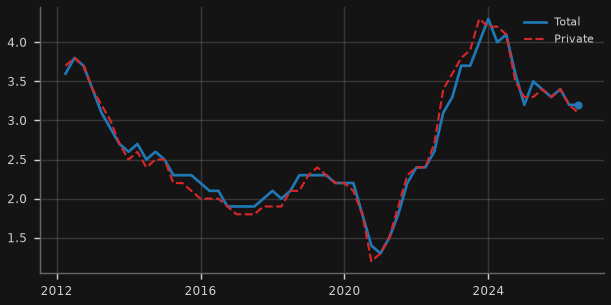
Why it matters for Australia: Wage growth vs mortgage rates determines whether borrowers' real debt burden is easing.
Rule: Heating > 3.5%; cooling < 2.5%; otherwise steady (RBA consistent range roughly 3-3.5%).
Source: RBA table H4: GWPIYP, GWPIPRIYP
3.5% -1.2pp over 1y
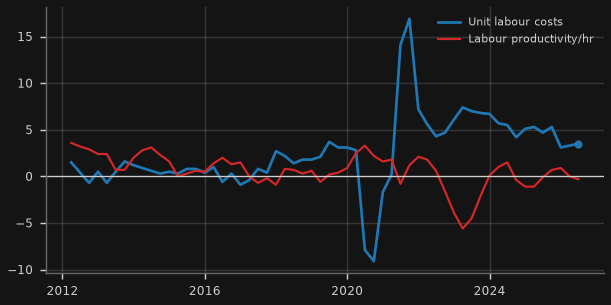
Why it matters for Australia: Weak productivity keeps unit labour costs (and so core inflation) sticky, which keeps real rates high.
Rule: Non-farm ULC y/y: heating > 4%; cooling < 2%; otherwise steady.
Source: RBA table H4: GNFULCYP, GNFPROSQP
Inflation
Trimmed mean CPI (y/y)HEATING
3.6% +0.1pp over 3m
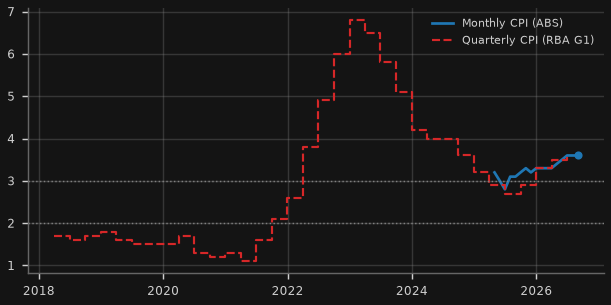
Why it matters for Australia: Core inflation sets the RBA path and hence the real cash rate borrowers face.
Rule: Heating > 3%; cooling < 2%; otherwise steady (RBA target band 2-3%).
Caveat: ABS complete monthly CPI only starts Apr-2025; longer history uses the quarterly series (not spliced).
Source: ABS Data API (CPI,2.0.0): 3.{999902|10001}.{20|10}.50.M; RBA table G1: GCPIOCPMTMYP
Headline CPI (y/y)HEATING
4.0% +0.0pp over 3m
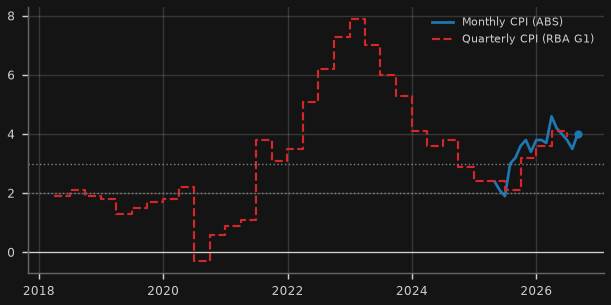
Why it matters for Australia: Headline drives inflation expectations and indexation of rents/wages.
Rule: Heating > 3%; cooling < 2%; otherwise steady.
Caveat: Electricity rebates distort headline in 2024-26.
Source: ABS Data API (CPI,2.0.0): 3.{999902|10001}.{20|10}.50.M; RBA table G1: GCPIAGYP
3.7% +0.0pp over 3m
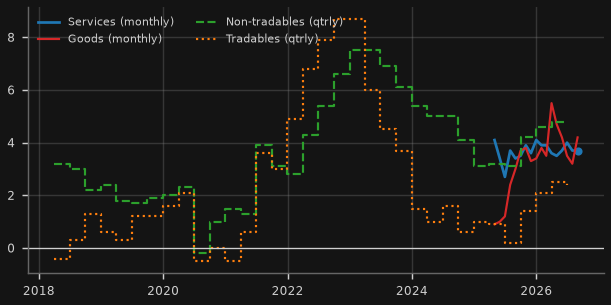
Why it matters for Australia: Services inflation is domestic and labour-driven: the part the RBA can't import away.
Rule: Services y/y: heating > 4%; cooling < 2.5%; otherwise steady.
Source: ABS Data API (CPI,2.0.0): 3.104104+104101.10.50.M; RBA table G1: GCPINTIYP, GCPITIYP
3.6% +0.0pp over 3m
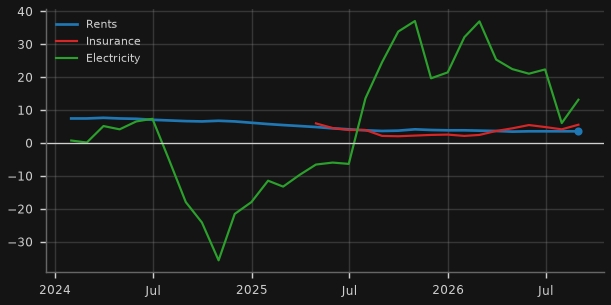
Why it matters for Australia: Rents feed directly from housing undersupply; insurance and power are the cost-of-living pinch points.
Rule: Rents y/y: heating > 5%; cooling < 2%; otherwise steady.
Caveat: Electricity y/y heavily affected by government rebate timing.
Source: ABS Data API (CPI,2.0.0): 3.115522+115528+40055.10.50.M
4.9% +0.2pp over 1y
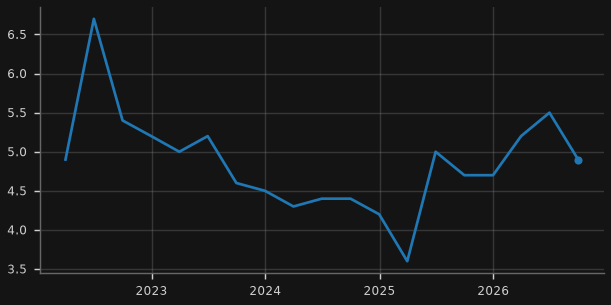
Why it matters for Australia: Elevated expectations make the RBA slower to cut, keeping real rates high.
Rule: Heating > 5%; cooling < 3.5%; otherwise steady.
Caveat: Melbourne Institute survey; median-based, structurally above actual inflation.
Source: RBA table G3: GCONEXP
Rates, credit & funding
Cash 4.60% (12 Oct 2026) +0.2pp over 1y
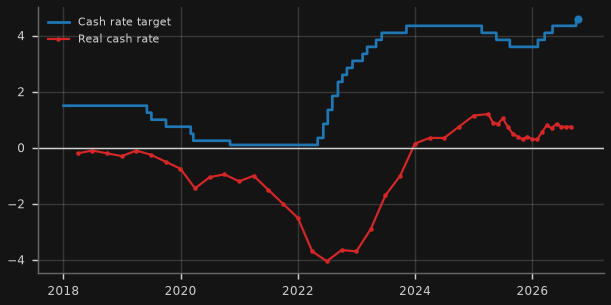
Why it matters for Australia: Core of the thesis: a positive real cash rate is what squeezes credit-financed assets.
Rule: Real cash rate (cash target minus latest trimmed-mean y/y): cooling (restrictive) if > 1pp; heating (stimulatory) if < 0; otherwise steady.
Caveat: Real rate uses quarterly trimmed mean before Apr-2025 and monthly after; points only where inflation is observed (no interpolation).
Source: RBA table F1: FIRMMCRTD; RBA table G1: GCPIOCPMTMYP; ABS Data API (CPI,2.0.0): 3.999902.20.50.M
AGS 3y & 10y yieldsHEATING
4.93% +51bp over 3m
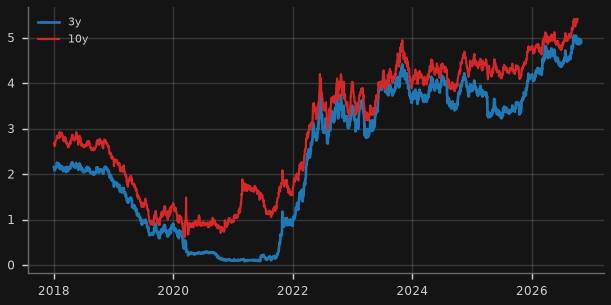
Why it matters for Australia: The 3y prices the RBA path (and fixed mortgage rates); the 10y links Australia to global term premia.
Rule: 3y yield 3-month change: heating if >= +40bp (market pricing tighter policy); cooling if <= -40bp; otherwise steady.
Source: RBA table F2: FCMYGBAG3D, FCMYGBAG10D
AGS 10y-3y curveSTEADY
+0.47 pp +4bp over 3m
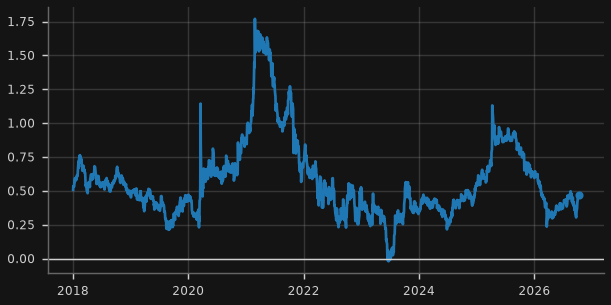
Why it matters for Australia: An inverted curve says markets expect policy to be cut as growth weakens.
Rule: Cooling if inverted (< 0); heating if > 1.25pp (steep, reflationary); otherwise steady.
Source: RBA table F2: FCMYGBAG3D, FCMYGBAG10D
3.00% +48bp over 3m
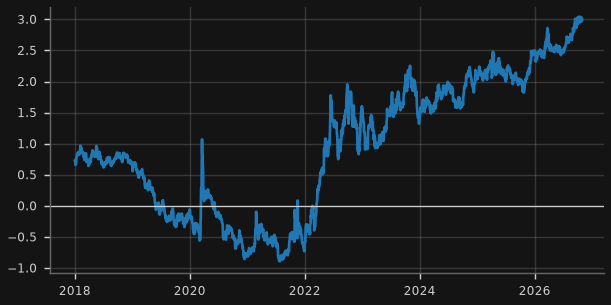
Why it matters for Australia: Real long rates discount every asset: high real yields pressure property and leveraged valuations.
Rule: Cooling (restrictive) if > 2%; heating if < 1%; otherwise steady.
Caveat: RBA 'indexed bond' series (approx. 10y target tenor).
Source: RBA table F2: FCMYGBAGID
+0.17 pp +5bp over 3m
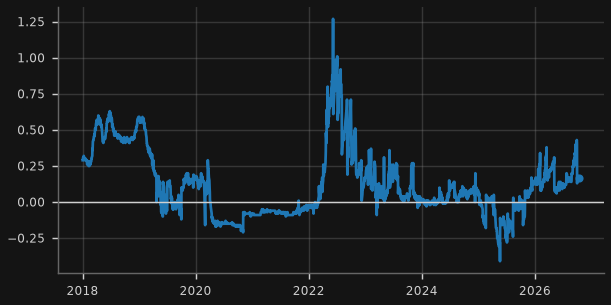
Why it matters for Australia: Bank funding pressure passes straight into business and non-bank lending rates.
Rule: Stress if > 0.40pp; cooling (market pricing cuts) if < -0.20pp; otherwise steady.
Caveat: Proxy for BBSW-OIS: RBA stopped publishing OIS rates in Dec-2022, so the spread also embeds expected cash-rate moves over 3 months.
Source: RBA table F1: FIRMMBAB90D, FIRMMCRTD
1.09 pp +14bp over 3m
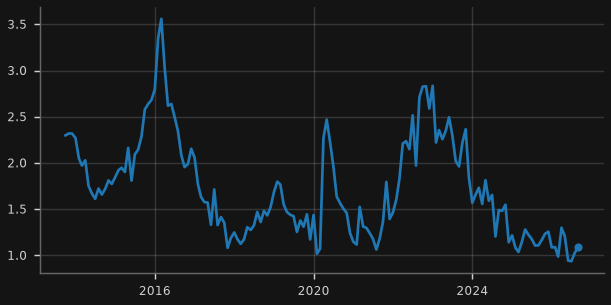
Why it matters for Australia: Corporate credit spreads show whether investors are demanding more to lend to Australian business.
Rule: Percentile of trailing 10 years: stress >= 90th; cooling 70-90th (credit tightening); heating <= 20th (very tight spreads = easy credit); otherwise steady.
Caveat: Spread computed by subtracting monthly 5y AGS yield from RBA BBB non-financial corporate 5y yield.
Source: RBA table F3: FNFYBBB5M; RBA table F2.1: FCMYGBAG5
Housing credit growth (y/y)COOLING
7.3% +1.2pp over 1y
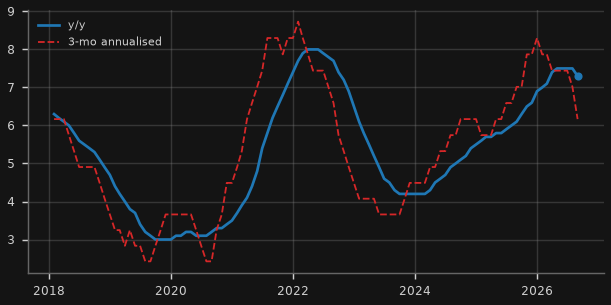
Why it matters for Australia: Housing credit is ~60% of private credit: its pace is the pulse of the leveraged-household thesis.
Rule: Heating if y/y > 10% or 3-mo annualised growth exceeds y/y by > 1pp (accelerating); cooling if 3-mo annualised is > 1pp below y/y (decelerating); otherwise steady.
Caveat: RBA D1 growth rates are break-adjusted.
Source: RBA table D1: DGFACH12, DGFACHM
9.6% +2.6pp over 1y
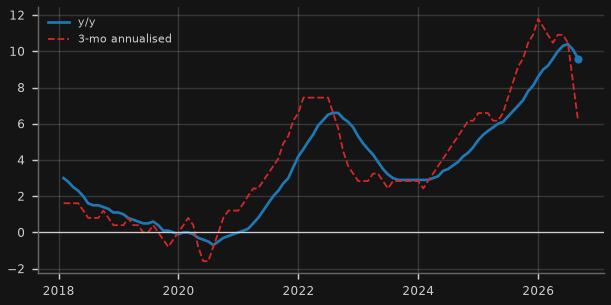
Why it matters for Australia: Investor credit is the speculative, rate-sensitive margin of the housing market.
Rule: Heating if y/y > 10% or 3-mo annualised growth exceeds y/y by > 1pp (accelerating); cooling if 3-mo annualised is > 1pp below y/y (decelerating); otherwise steady.
Caveat: RBA D1 growth rates are break-adjusted.
Source: RBA table D1: DGFACIH12, DGFACIHM
Business credit growth (y/y)HEATING
10.9% +1.1pp over 1y
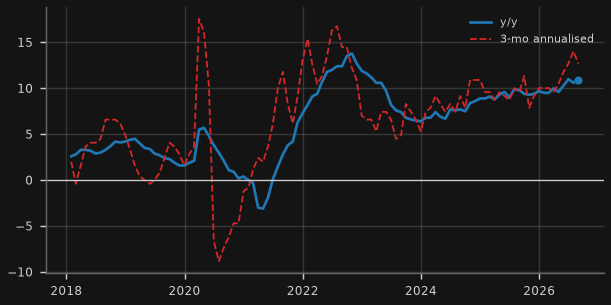
Why it matters for Australia: Business credit includes lending to non-bank lenders and property; fast growth late in a cycle is a risk flag.
Rule: Heating if y/y > 10% or 3-mo annualised growth exceeds y/y by > 1pp (accelerating); cooling if 3-mo annualised is > 1pp below y/y (decelerating); otherwise steady.
Caveat: RBA D1 growth rates are break-adjusted.
Source: RBA table D1: DGFACBNF12, DGFACBNFM
6.20% +70bp over 1y
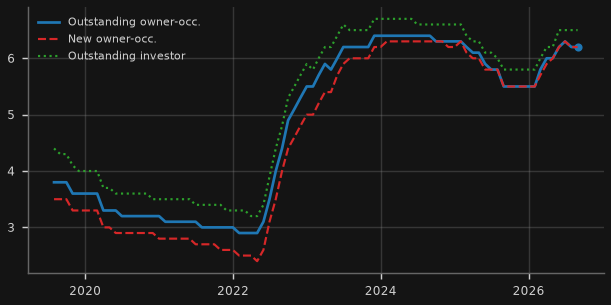
Why it matters for Australia: Mortgage rate minus core inflation = the real burden on the household balance sheet.
Rule: Real mortgage rate (outstanding owner-occupier variable minus trimmed-mean y/y): cooling (restrictive) if > 3pp; heating if < 1pp; otherwise steady.
Source: RBA table F6: FLRHOOVA, FLRHOFVA, FLRHIOVA
Total business finance 11.9% y/y +1.5pp over 1y
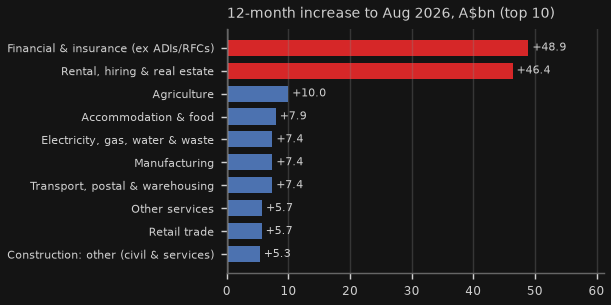
Why it matters for Australia: Shows whether new business credit funds productive capacity or property/financial intermediaries (incl. private credit funds).
Rule: Context only (no traffic light).
Caveat: RBA D14.1 is NSA and not break-adjusted; 'Financial & insurance' includes lending to non-bank financiers/funds.
Source: RBA table D14.1: industry series (via ../credit-growth-au); RBA table D14: DLBOST+DLBOMT+DLBOLT
97.6 A$bn +6.8% over 1y
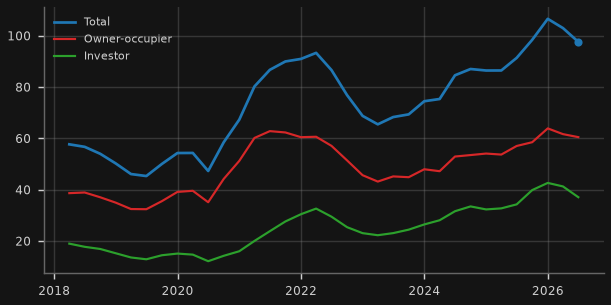
Why it matters for Australia: New lending is the flow that sets house prices at the margin.
Rule: Total value y/y: heating > +10%; cooling < -10%; otherwise steady.
Caveat: Total dwellings excluding refinancing; seasonally adjusted; ABS publishes this series quarterly.
Source: ABS Data API (LEND_HOUSING): FIN_VAL.NEWCOMMITS.*.TOTDWELL.TOT.TOT+DV5167+DV5168.20.AUS.Q
10.7% +3.8pp over 1y
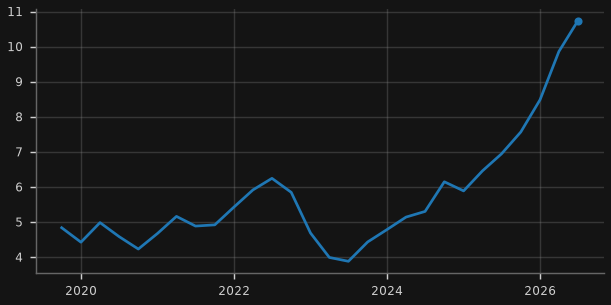
Why it matters for Australia: Rising non-bank share means more housing risk sits outside APRA's prudential perimeter.
Rule: Heating if share up >= 1pp y/y (non-bank lending gaining share); cooling if down >= 1pp; otherwise steady.
Caveat: Seasonally adjusted values, dwellings excluding refinancing; ABS non-ADI coverage is registered financial corporations reporting to APRA, not all private credit.
Source: ABS Data API (LEND_HOUSING): FIN_VAL.NEWCOMMITS.*.TOTDWELL.NON_ADI+TOT.TOT.20.AUS.Q
Housing
6.8% -3.2pp over 3m
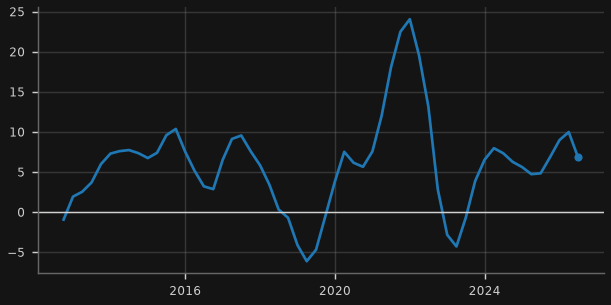
Why it matters for Australia: Housing is the dominant collateral in the Australian credit system.
Rule: Heating > 7% y/y; steady 0-7%; cooling -5% to 0; stress < -5%.
Caveat: ABS quarterly with ~3-month lag; monthly Cotality index is not free (see au_housing_outlook.md for its latest prints).
Source: ABS Data API (RES_DWELL_ST,1.0.0): 5.AUS (mean price $'000)
17.9 '000 +4.7% over 6m
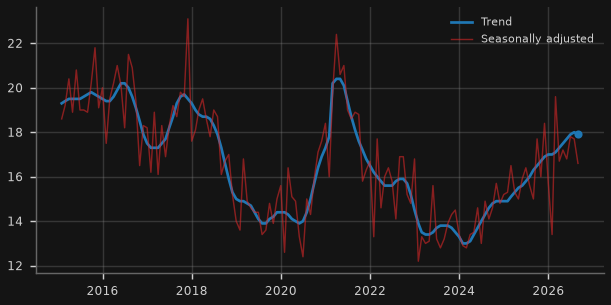
Why it matters for Australia: Approvals lead construction activity and the developer finance pipeline (where private credit is exposed).
Rule: Trend, 6-month change: heating > +5%; cooling < -5%; otherwise steady.
Source: RBA table H3: GISPSDA, GISDWPRITR
204 '000 +13.2% over 1y
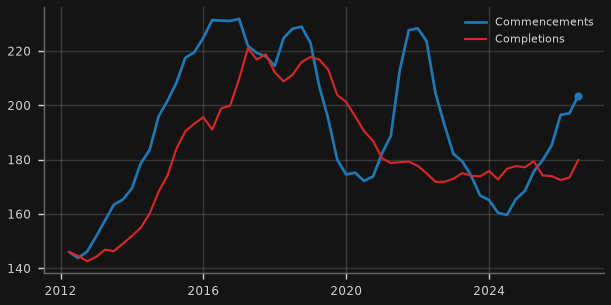
Why it matters for Australia: Supply response: weak starts keep rents/prices firm but signal developer stress.
Rule: Commencements 4-qtr sum y/y: heating > +5%; cooling < -5%; otherwise steady.
Caveat: Total residential, total sectors; ABS quarterly with ~3-month lag. Under construction is original series.
Source: ABS Data API (BUILDING_ACTIVITY): M6+M7+M8.AUS..TOT/1.9.100.{20|10}.Q
Activity & stress
6.8% +2.1pp over 1y
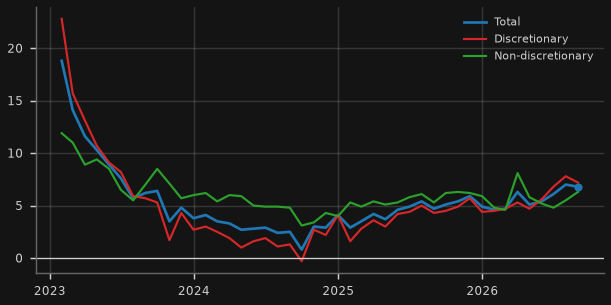
Why it matters for Australia: Consumption is ~half of GDP; discretionary spending is where rate pain shows first.
Rule: Approx. real growth (HSI y/y minus monthly CPI y/y): heating > 3%; cooling < 0.5%; otherwise steady.
Caveat: Nominal; real approximation subtracts headline monthly CPI (crude deflator).
Source: ABS Data API (HSI_M,1.6.0): 9.TOT+3+4.CUR.20.AUS.M
Household saving ratioSTEADY
6.5% +0.6pp over 1y
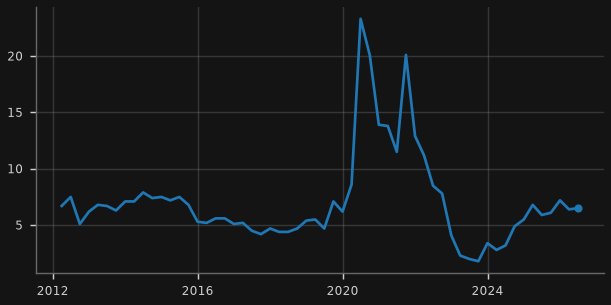
Why it matters for Australia: A thin saving buffer leaves households less able to absorb high rates; a jump signals precautionary retrenchment.
Rule: Cooling if up >= 1pp y/y (precautionary saving); heating if down >= 1pp y/y; otherwise steady.
Source: RBA table H2: GGDPICHDISR
0.7% +0.3pp over 1y
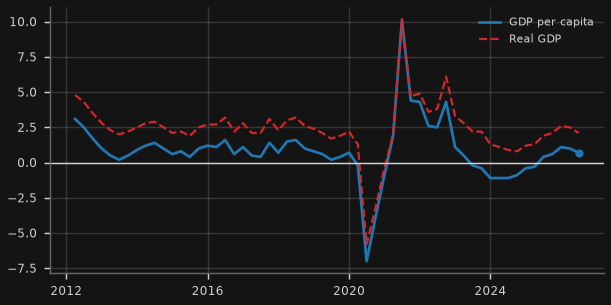
Why it matters for Australia: Per-capita GDP strips out population growth: the 'per-capita recession' test.
Rule: GDP per capita y/y: cooling < 0%; heating > 2%; otherwise steady.
Source: RBA table H1: GGDPCVGDPY, GGDPCVGDPFY
NAB business conditionsCOOLING
-4.2 net bal. -3.7 over 3m
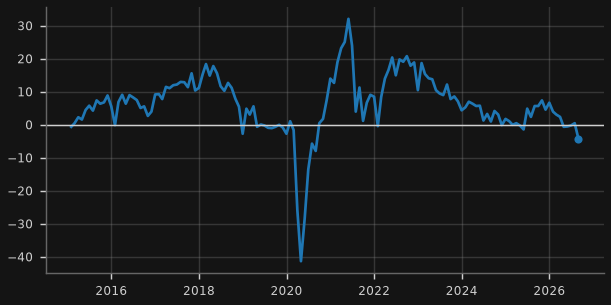
Why it matters for Australia: Business conditions lead hiring and investment.
Rule: Heating > +10; cooling < 0; otherwise steady.
Source: RBA table H3: GICNBC
80.4 -3.5 over 3m
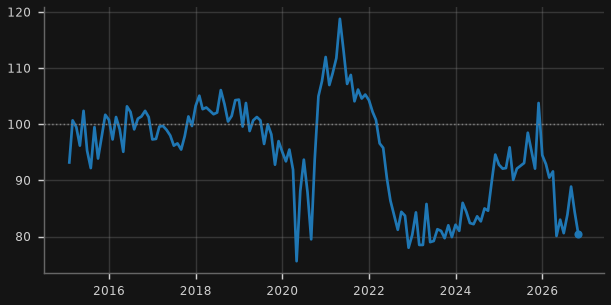
Why it matters for Australia: Sentiment below 100 = pessimists outnumber optimists; deep lows often coincide with rate stress.
Rule: Heating > 100; cooling < 90; otherwise steady.
Caveat: Latest point is the October 2026 survey (fieldwork 28 Sep-1 Oct, released 7 Oct; straddles the 30 Sep RBA hike). RBA stamps it 31 Oct. Verified against Westpac's release: 80.4, down from 84.4.
Source: RBA table H3: GICWMICS
1808 count/mo 3-mo sum +16% y/y
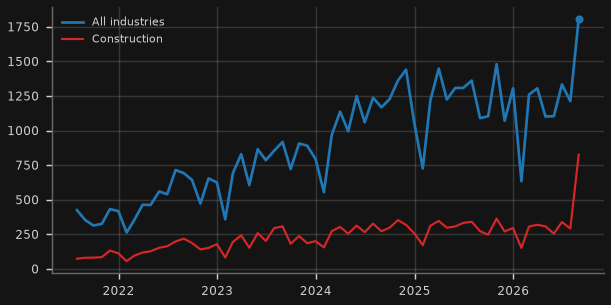
Why it matters for Australia: Insolvencies are where high real rates and private-credit refinancing stress become visible.
Rule: 3-month sum y/y: stress > +25%; cooling +5% to +25%; otherwise steady.
Caveat: Partial latest month dropped (data to 27 Sep 2026). Aug-2026 construction includes 542 entities of one group (Bathla) entering administration together.
Source: ASIC insolvency statistics Series 1 & 2 (xlsx): Series 1: companies entering external administration
External & commodities
Terms of trade (index)STEADY
94.8 -0.5% over 1y
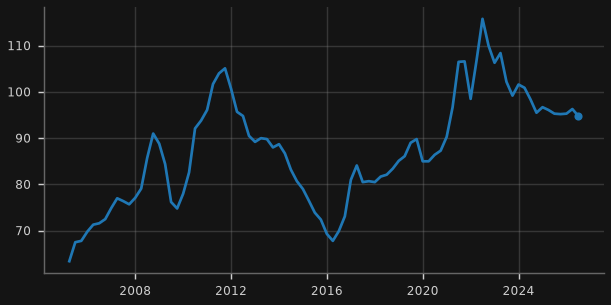
Why it matters for Australia: Export prices vs import prices: the main channel from China's demand to Australian national income and the budget.
Rule: y/y: heating > +5%; cooling < -5%; otherwise steady.
Source: RBA table H1: GOPITT
-3.7 % GDP -1.3 over 1y
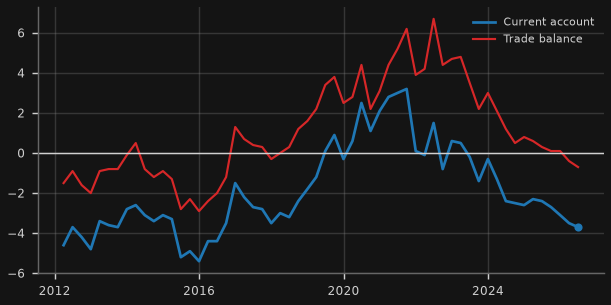
Why it matters for Australia: A widening deficit means more reliance on foreign capital (and sensitivity to global funding costs).
Rule: Context only (no traffic light).
Source: RBA table I1: HCAGSCPGDP, HTBGSCPGDP
106.6 +6.6% over 1y
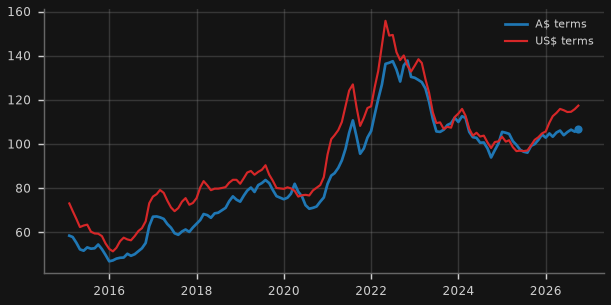
Why it matters for Australia: Commodity prices in A$ drive mining profits, tax receipts and the AUD.
Rule: A$ index y/y: heating > +10%; cooling < -10%; otherwise steady.
Source: RBA table I2: GRCPAIAD, GRCPAIUSD
Iron ore (US$/t)STEADY
98 US$ -5.4% over 1y
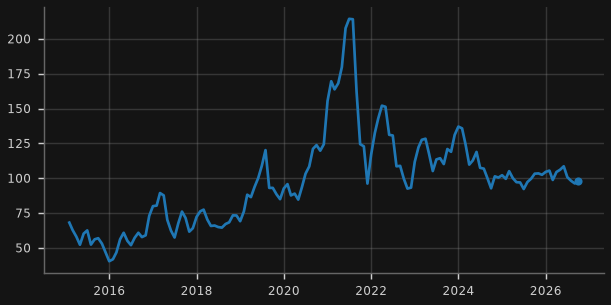
Why it matters for Australia: Australia's largest export; priced off Chinese steel demand.
Rule: y/y: heating > +10%; cooling < -10%; otherwise steady.
Caveat: Monthly average prices.
Source: World Bank Pink Sheet (CMO historical monthly): Iron ore, cfr spot
147 US$ +38.4% over 1y
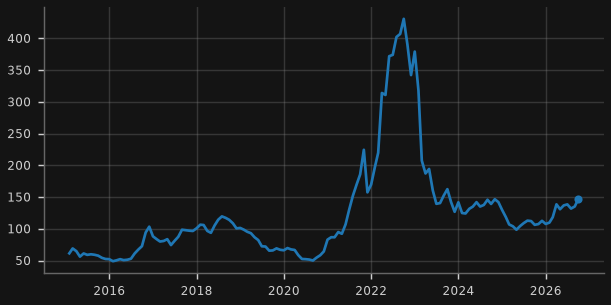
Why it matters for Australia: Coal exports go mostly to Japan, China, Korea, India and Taiwan.
Rule: y/y: heating > +10%; cooling < -10%; otherwise steady.
Caveat: Monthly average prices.
Source: World Bank Pink Sheet (CMO historical monthly): Coal, Australian
14.25 US$ +24.2% over 1y
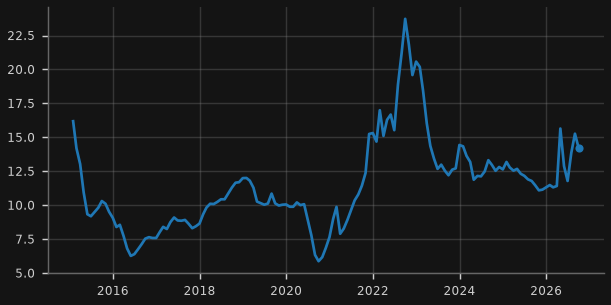
Why it matters for Australia: LNG is a top-3 export; Japan/Korea/China are the buyers.
Rule: y/y: heating > +10%; cooling < -10%; otherwise steady.
Caveat: Monthly average prices.
Source: World Bank Pink Sheet (CMO historical monthly): Liquefied natural gas, Japan
Gold (US$/oz)HEATING
4,319 US$ +17.7% over 1y
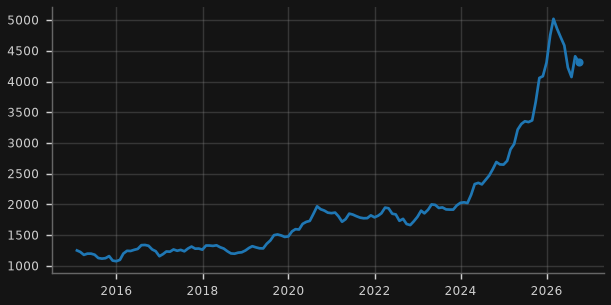
Why it matters for Australia: Gold is now a top-3 Australian export and a hedge against real-rate/USD shocks.
Rule: y/y: heating > +10%; cooling < -10%; otherwise steady.
Caveat: Monthly average prices.
Source: World Bank Pink Sheet (CMO historical monthly): Gold
0.6961 US$ -0.5% over 3m
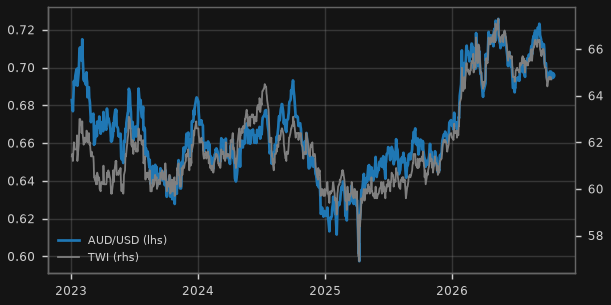
Why it matters for Australia: The AUD is the shock absorber: it falls when China/commodities or global risk appetite weaken.
Rule: TWI 3-month change: stress if <= -5% (risk-off); heating if >= +5%; otherwise steady.
Source: RBA table F11.1: FXRUSD, FXRTWI
AUD/CNY 4.661, AUD/JPY 110.17 -1.6% over 3m
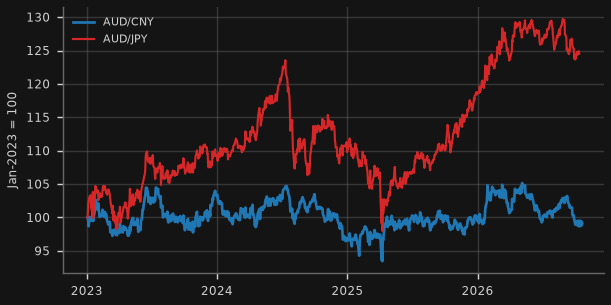
Why it matters for Australia: AUD/CNY tracks export competitiveness into China; AUD/JPY is the classic carry/risk barometer.
Rule: Context only (no traffic light).
Source: RBA table F11.1: FXRCR, FXRJY
35.2% +1.8pp over 1y
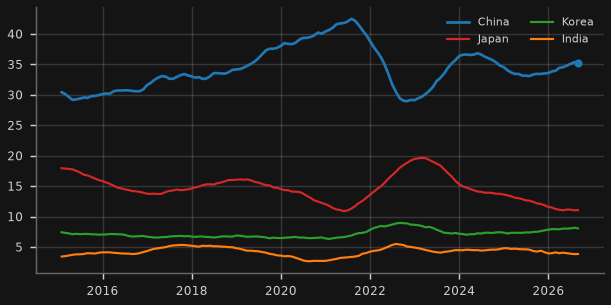
Why it matters for Australia: Concentration risk: roughly a third of goods exports go to one economy.
Rule: Context only (no traffic light).
Caveat: Goods only, A$ values; 12-month rolling sums.
Source: ABS Data API (MERCH_EXP): TOT.CHIN+TOT+JAP+RKOR+INIA.TOT.M
Financial stress
1.645 A$ -6.0% over 1m
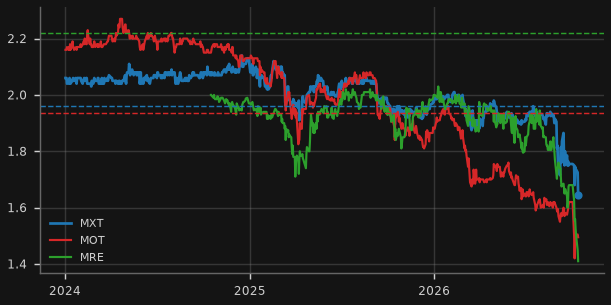
Why it matters for Australia: Discounts to NTA on listed private-credit vehicles are the market's live read on loan-book quality.
Rule: Worst discount to latest NTA: stress if > 10%; cooling if 5-10%; otherwise steady.
Caveat: NTAs are MANUAL inputs: audited 30-Jun-2026 values (MXT 1.9617, MOT 1.9346, MRE 2.22) after audit write-downs announced 28 Sep; units were suspended 28 Sep to 5 Oct. NTA is ~3 months old, and monthly NTA reporting resumes, so update MANUAL_NTA. Prices from unofficial Yahoo endpoint.
Source: Yahoo Finance chart endpoint (unofficial): MXT.AX, MOT.AX, MRE.AX; Manual input: audited NTA per unit at 30 Jun 2026 (ASX announcements, 28 Sep-5 Oct 2026): MANUAL_NTA in indicators.py
ASX 200 and financialsSTEADY
8,784 -0.6% over 3m
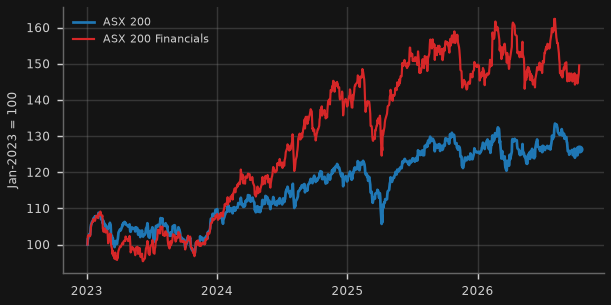
Why it matters for Australia: Bank and broad-equity drawdowns tighten financial conditions and wealth effects.
Rule: ASX 200: stress if >= 20% below 52-week high; cooling if 10-20% below; heating if within 2% of the 52-week high; otherwise steady.
Source: Yahoo Finance chart endpoint (unofficial): ^AXJO, ^AXFJ
ASX 200 A-REITsSTRESS
3,236 -8.8% over 3m
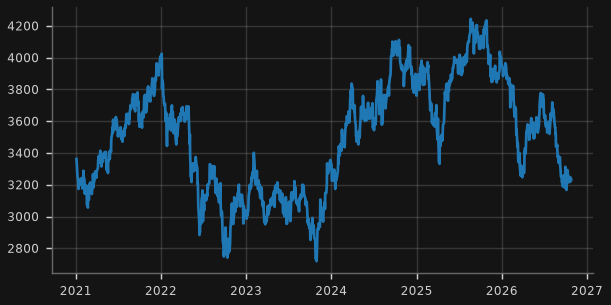
Why it matters for Australia: Listed property is the most rate-sensitive equity sector and marks commercial property in real time.
Rule: A-REIT index: stress if >= 20% below 52-week high; cooling if 10-20% below; heating if within 2% of the 52-week high; otherwise steady.
Source: Yahoo Finance chart endpoint (unofficial): ^AXRE
RBA Chart Pack highlights
Selected indicators from the RBA Chart Pack that aren't shown elsewhere on this dashboard, rebuilt from the RBA's public statistical tables (and FRED for US Treasuries). Each card's Takeaway is written from the latest values.
0heating 2steady 2cooling 0stress
Household balance sheet
178.4% +1.5pp over 1y
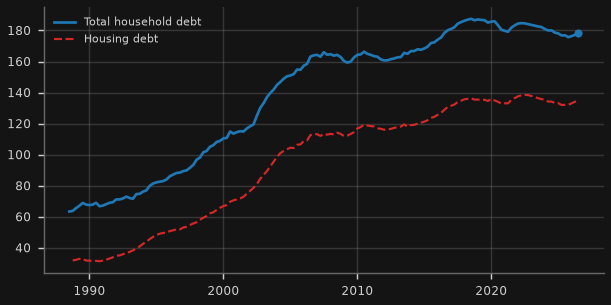
Takeaway: Household debt is 178% of annual disposable income (Q2 2026), housing debt 135%; down 9pp from the post-2015 peak of 188% (Q2 2018).
Why it matters for Australia: Australian households carry some of the highest debt loads in the world; the ratio sets how hard each rate move bites.
Rule: Context only.
Caveat: Full E2 history from 1988 (quarterly, annualised income); no splice. Series revised with ABS national accounts benchmarks.
Source: RBA table E2: BHFDDIT, BHFDDIH
16.1% -0.3pp over 1y
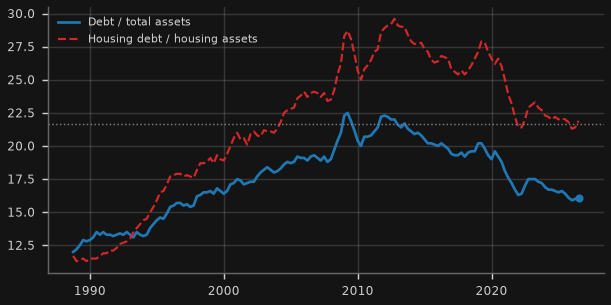
Takeaway: Debt is 16.1% of household assets and housing debt 21.9% of housing assets: housing gearing is below its post-2010 average (25.5%).
Why it matters for Australia: Gearing shows how much equity cushion sits under household debt if house prices fall.
Rule: Context only.
Caveat: Full E2 history from Sep 1988; dotted line = housing gearing average since 1988.
Source: RBA table E2: BHFDA, BHFHDHA
9.4% -0.5pp over 1y
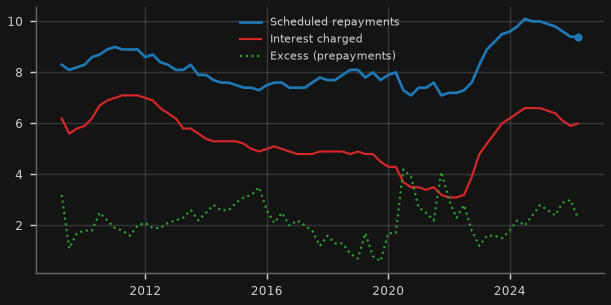
Takeaway: Scheduled mortgage repayments take 9.4% of disposable income (Q1 2026), of which interest 6.0%; borrowers are still paying an extra 2.3% ahead of schedule, and 56% of loans have an offset account.
Why it matters for Australia: The household debt-servicing ratio: the share of income committed to mortgages, the main channel of monetary policy.
Rule: Scheduled repayments vs 10-year average: cooling (restrictive) if >= 1pp above; heating if >= 1pp below; otherwise steady.
Caveat: E13 starts Mar 2009 (short by nature: built from post-GFC lender data; no earlier RBA table on this definition). Offset-account share starts Sep 2019.
Source: RBA table E13: LPHTSPRI, LPHTICRI, LPHTEXRI, HSHTOF
Lending rates vs the cash rate
7.47% +57bp over 1y
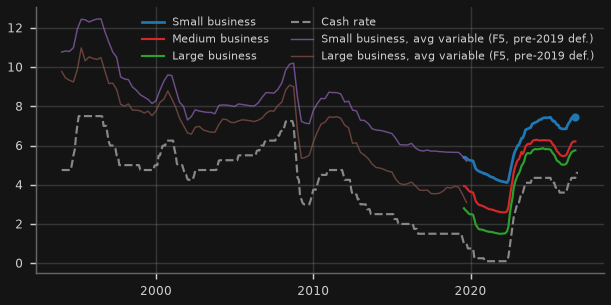
Takeaway: Small businesses pay 7.47% on outstanding loans vs 5.75% for large firms (Aug 2026): a 172bp size premium, with the cash rate at 4.35% that month.
Why it matters for Australia: Small firms pay well above large ones; that premium is how tight policy reaches the SME and non-bank lending market.
Rule: Context only.
Caveat: Break: F7 size-based rates (EFS collection) start Jul 2019 and are short by nature; earlier history uses the older F5 weighted-average variable rates (small business from Dec 1993, large from 1978), a different definition, shown as thin lines and not spliced. Cash rate: F1.1 target from Aug 1990, interbank overnight rate before.
Source: RBA table F7: FLRBFOSBT, FLRBFOMBT, FLRBFOLBT; RBA table F5: FILRSBVWA, FILRLBWAV; RBA table F1.1: FIRMMCRT, FIRMMCRI; RBA table F1: FIRMMCRTD
1.85 pp -5bp over 1y
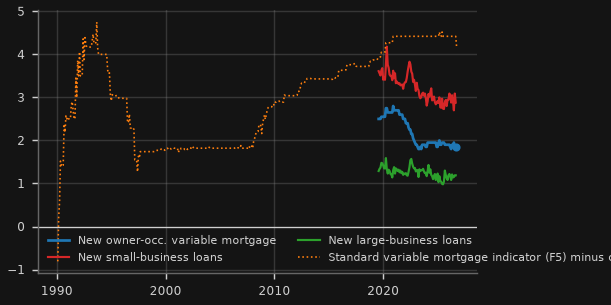
Takeaway: New variable mortgages are priced 1.85pp over the cash rate (Aug 2026), narrower than the 2.53pp pre-COVID average; new small-business loans 2.88pp.
Why it matters for Australia: Spreads over the cash rate show whether banks are passing on policy fully, or competing margins away.
Rule: Context only.
Caveat: Break: F6/F7 new-loan rates (EFS) start Jul 2019 (short by nature). Longer context is the F5 banks' standard variable housing indicator rate minus the cash rate (from 1990), a headline rather than actual-paid rate, so not spliced.
Source: RBA table F6: FLRHOFVA; RBA table F5: FILRHLBVS; RBA table F1.1: FIRMMCRT, FIRMMCRI; RBA table F7: FLRBFNSBT, FLRBFNLBT; RBA table F1: FIRMMCRTD
Money & markets
6.9% +0.1pp over 1y
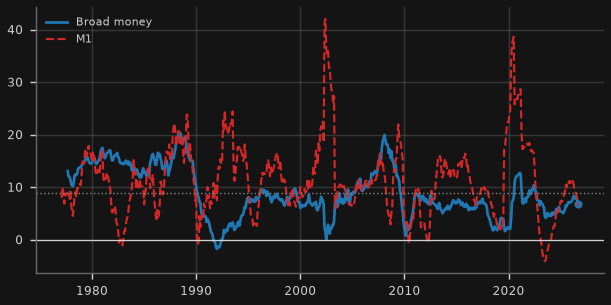
Takeaway: Broad money is growing 6.9% a year and M1 6.5% (Aug 2026).
Why it matters for Australia: Deposits are the other side of bank lending; M1 (transaction balances) swings with rates as savers shift to term deposits.
Rule: Broad money y/y: heating > 9%; cooling < 4%; otherwise steady.
Caveat: Full D3 history (broad money from Aug 1976, M1 from 1975). Growth is from levels, not break-adjusted: reclassifications (e.g. 1980s bank/NBFI conversions, 2019 EFS) cause jumps. Dotted line = broad-money average since 1977.
Source: RBA table D3: DMABMS, DMAM1S
0.18 pp +0bp over 1y
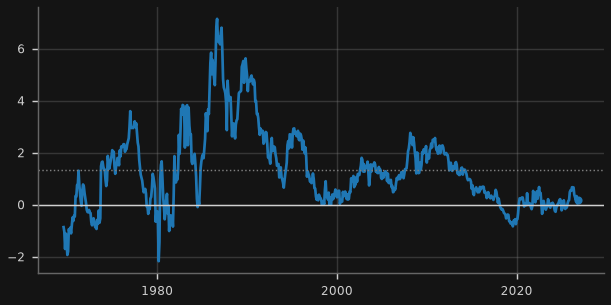
Takeaway: AGS 10y 5.40% vs US 10y 5.28%: Australia yields +12bp over Treasuries (07 Oct 2026), vs a 10-year average of +3bp.
Why it matters for Australia: A positive AU-US spread pulls in foreign capital and supports the AUD; it also tells you whether local long rates are being set offshore.
Rule: Context only.
Caveat: Spliced: F2 historical table (f02histhist, month-end, Jul 1969-Apr 2013) + current F2 daily from May 2013 taken at month-end; same 10y benchmark definition. US: FRED DGS10 month-end. Dotted line = average since 1969.
Source: RBA table F2: FCMYGBAG10D; RBA historical table F2 (1969-2013): FCMYGBAG10; FRED (St Louis Fed): DGS10
Inflation & wages
-0.7 pp -2.0pp over 1y
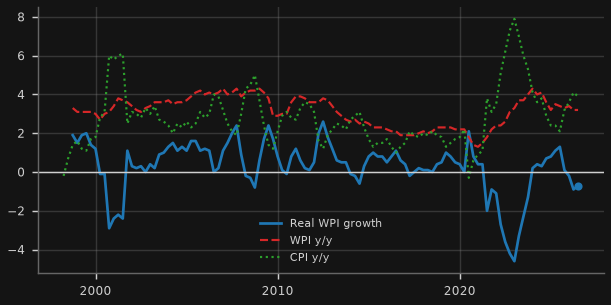
Takeaway: Wages rose 3.2% against 3.9% inflation over the year to Q2 2026: real wages down 0.7%.
Why it matters for Australia: Real wages decide whether households can grow out of their debt; they fell sharply in 2022-23.
Rule: Heating > +1.5pp; cooling < 0; otherwise steady.
Caveat: Starts Sep 1998: the ABS Wage Price Index begins in 1997 (first y/y 1998), so this is short by nature; CPI (G1) goes back to 1923.
Source: RBA table H4: GWPIYP; RBA table G1: GCPIAGYP
2.5% -0.1pp over 1y
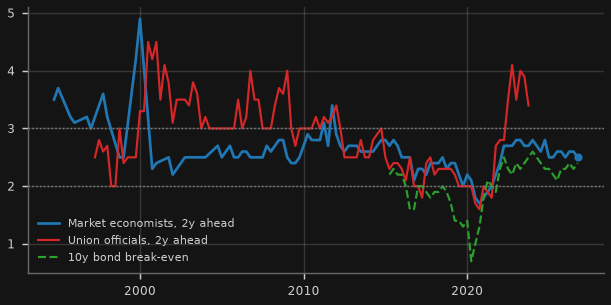
Takeaway: Economists expect 2.5% inflation in two years, unions 3.4%, and bond markets price 2.4% over ten years (Q3 2026): inside the 2-3% target band.
Why it matters for Australia: If 2-year and 10-year expectations stay near 2.5%, the RBA can look through one-off price shocks.
Rule: Market economists 2y ahead: heating > 3%; cooling < 2%; otherwise steady.
Caveat: Full G3 history: economists' survey from 1994, union officials from 1997; the 10y break-even series in G3 starts 2015 (short by nature). No splice.
Source: RBA table G3: GMAREXPYY, GUNIEXPYY, GBONYLD
Australian funding & liquidity
How the Australian dollar money market is working: the overnight cash market, the RBA's open market operations, banks' Exchange Settlement (ES) balances, the Term Funding Facility run-off and bank bill funding spreads, rebuilt from the RBA's public statistical tables (F1, A1, A2, A3). Each card's Takeaway is written from the latest values.
0heating 0steady 0cooling 0stress
Overnight cash market
1,267 $m -380.9 over 1y
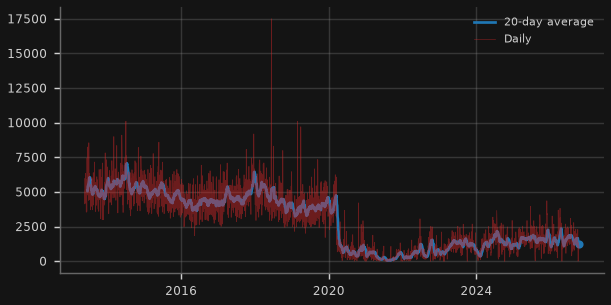
Takeaway: About $1.3b a day now trades in the overnight cash market (12 Oct 2026, 20-day average), well below the 2019 average of $3.9b: banks still hold ample reserves, so few need to borrow overnight.
Why it matters for Australia: When the RBA floods banks with reserves they no longer need to borrow overnight from each other, so the cash market shrinks.
Rule: Context only.
Caveat: RBA publishes cash market volumes only from 20 May 2013 (F1, short by nature).
Source: RBA F1 Money market (daily): FIRMMCRIV
+0 bp +0bp over 1y
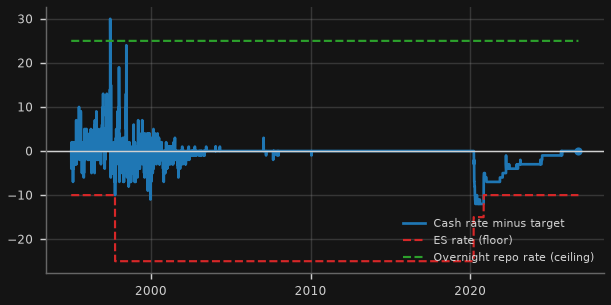
Takeaway: The cash rate is 4.60% vs a 4.60% target (+0bp, 12 Oct 2026), sitting close to the floor (floor -10bp, ceiling +25bp): the hallmark of an ample-reserves system.
Why it matters for Australia: Where the cash rate sits between the ES deposit rate (floor) and the standing-facility repo rate (ceiling) shows whether reserves are scarce or ample.
Rule: Context only.
Caveat: Corridor from A2 administered rates (ES rate and standing-facility overnight repo rate) applied as step functions; daily cash rate spliced from the F1 historical xls (to 2010) and current F1 (2011+).
Source: RBA F1 / F1 historical (daily): FIRMMCRID, FIRMMCRTD; RBA A2 Administered rates: ARBAMPNRPESB, ARBAMPNORR
RBA open market operations
46.3 $b +14.7 over 1y
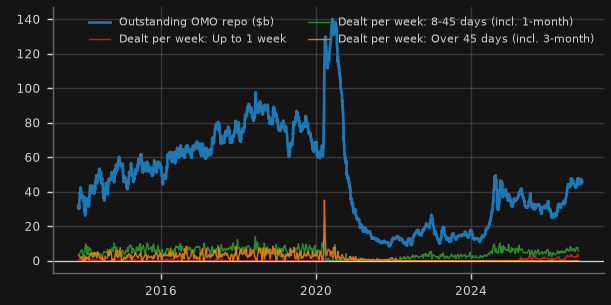
Takeaway: Banks have $46.3b of repo outstanding with the RBA (12 Oct 2026); over the last four weeks $28.5b was dealt at around 1 month and $0.0b at longer terms, vs $11.5b at a week or less.
Why it matters for Australia: Banks now get most of their marginal reserves by borrowing from the RBA at its weekly full-allotment repo operations rather than from each other.
Rule: Context only.
Caveat: A3 operations data start Nov 2013. Term buckets are grouped by the term of each transaction; outstanding = OMO reverse repo + triparty reverse repo (outright bond purchases excluded).
Source: RBA A3 ES balances and repo agreements: AORROMO, AORROMOTRI; RBA A3 OMO repo transaction details: AFROMOTD, AFROMOVD
+10 bp +0bp over 1y
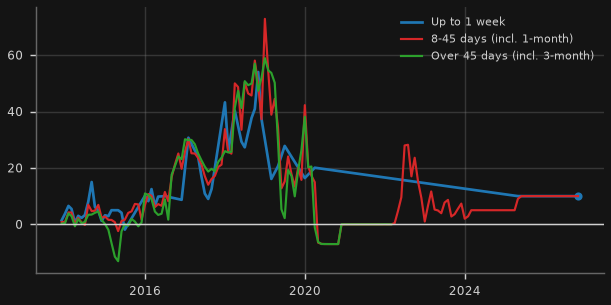
Takeaway: RBA repo at up to 1 week averaged +10bp over the cash rate target in Oct 2026; 8-45 days (incl. 1-month) +10bp (the RBA's full-allotment repo price), versus close to zero before 2020.
Why it matters for Australia: The price of RBA repo relative to the cash rate shows how much banks pay up for reserves; it rose as the RBA moved to a full-allotment system.
Rule: Context only.
Caveat: Value-weighted average across dealt repos: fixed-rate deals as rate minus the cash rate target on the deal date; floating-rate deals (the norm since Feb 2024) use the published spread to the cash rate target. Grouped by term bucket.
Source: RBA A3 OMO repo transaction details: AFROMOWAR, AFROMOVD, AFROMOTD; RBA F1 Money market (daily): FIRMMCRTD
Reserves, TFF and standing facility
196 $b -7.6 over 1y
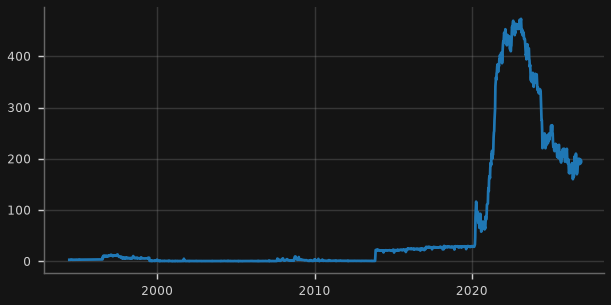
Takeaway: Banks hold $196b in ES balances (07 Oct 2026), down from the $473b peak (Feb 2023) but far above the roughly $29b of 2019.
Why it matters for Australia: ES balances are banks' reserves at the RBA; their surge after 2020 (bond buying and the TFF) is why the cash market went quiet.
Rule: Context only.
Caveat: Weekly A1 from Jul 2013, extended back to Jun 1994 with the RBA's historical A1 summary (same series ID).
Source: RBA A1 Balance sheet (weekly): ARBALESBW; RBA A1 historical summary 1994-2023: ARBALESBW
7.7 $b -170.1 over 1y
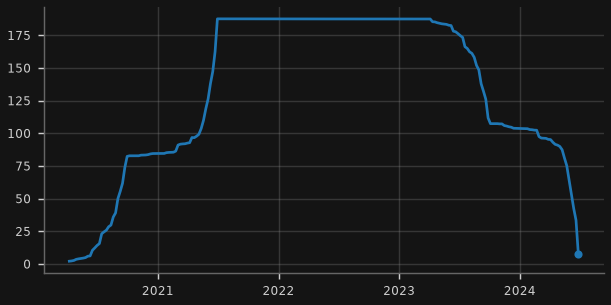
Takeaway: The TFF has fully run off: the last $7.7b was outstanding on 26 Jun 2024, down from a $188b peak (Jun 2021), and the RBA has published no balance since.
Why it matters for Australia: The TFF lent banks about $188b of cheap three-year money in 2020-21; its run-off forced banks to replace it with market funding and RBA repo.
Rule: Context only.
Caveat: Facility opened Apr 2020; drawdowns closed Jun 2021 and all funding matured by mid-2024 (short by nature).
Source: RBA A3 Term Funding Facility: ATFFOTD
0 $m +0.0 over 1y
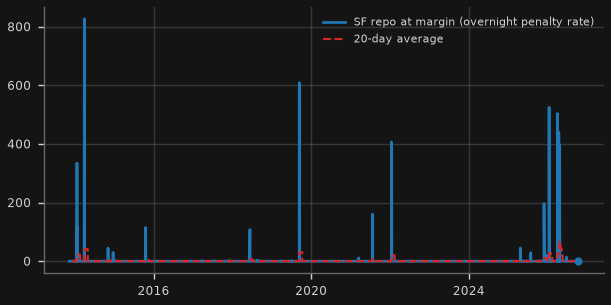
Takeaway: Overnight standing-facility borrowing at the ceiling rate was $0m on 12 Oct 2026 and was used on 12 of the last 250 business days, averaging $175m (max $525m) when used: no sign of system-wide stress. Separately, $4.2b of open (intraday-liquidity) repo sits at the ES rate.
Why it matters for Australia: Banks borrowing overnight from the RBA at the penalty (ceiling) rate signals an individual bank could not find cash in the market.
Rule: Context only.
Caveat: 'SF repos at margin' = standing-facility repos at the cash rate target plus margin; open repos at the ES rate (for RITS intraday liquidity) are reported separately and noted in the takeaway.
Source: RBA A3 ES balances and repo agreements: AORRLFPR, AORRLFCRT
Bank bill funding spreads
+17 bp +18bp over 1y
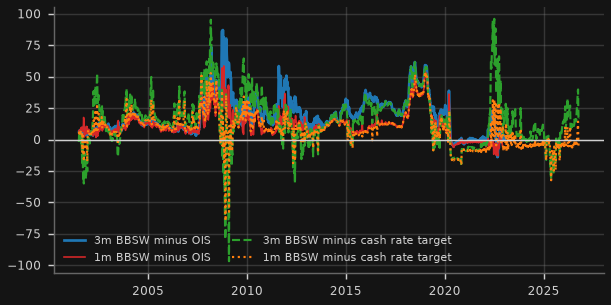
Takeaway: 3m BBSW is +17bp over the cash rate target and 1m -3bp (12 Oct 2026); the last published 3m BBSW-OIS spread was +2bp (Dec 2022) vs a GFC peak of +87bp.
Why it matters for Australia: BBSW over OIS strips out rate expectations to show pure bank credit and liquidity stress (GFC, 2020); after OIS data ends the gap to the cash rate target also reflects expected rate moves.
Rule: Context only.
Caveat: 5-day averages. RBA OIS (F1) runs Jul 2001 to 1 Dec 2022 only; after that only the BBSW minus cash rate target proxy is available (it embeds expected cash-rate changes). Bank bill rates spliced from F1 historical xls.
Source: RBA F1 / F1 historical (daily): FIRMMBAB30D, FIRMMBAB90D, FIRMMOIS1D, FIRMMOIS3D, FIRMMCRTD
China
2heating 7steady 1cooling 2stress
Credit & property
0.9 % GDP +1.6pp over 1y
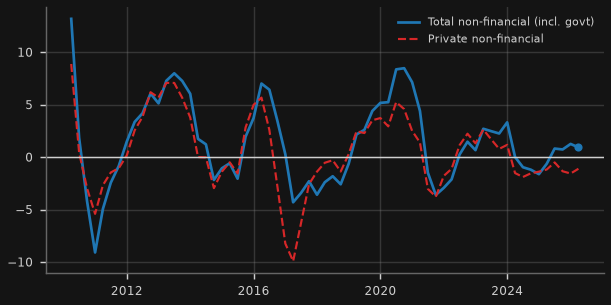
Why it matters for Australia: China's credit impulse has historically led its steel and construction demand, i.e. Australian iron ore volumes and prices, by 6-12 months.
Rule: 4-quarter change in 4-quarter credit flow as % of GDP: heating > +1pp; cooling < -1pp; otherwise steady. Rule applied to total non-financial sector (incl. government).
Caveat: Derived: GDP implied from BIS credit level / credit-to-GDP ratio. Proxy for TSF-based impulse (PBoC TSF not used). BIS data lag ~2 quarters.
Source: BIS Data Portal (WS_TC): Q.CN.C+P.A.M.XDC+770.A
-24.8% -2.2pp over 3m
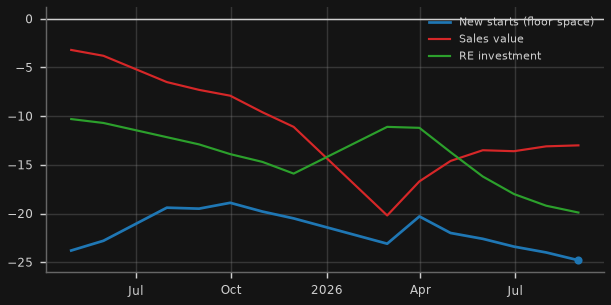
Why it matters for Australia: Chinese housing construction is the single biggest end-use of Australian iron ore.
Rule: New starts (floor space, YTD y/y): stress < -15%; cooling -15% to 0; heating > +5%; otherwise steady.
Caveat: Year-to-date cumulative growth rates; only releases since ~Aug-2025 parse fully.
Source: China NBS English press releases (scraped): Investment in Real Estate Development releases
-3.3% +0.4pp over 3m
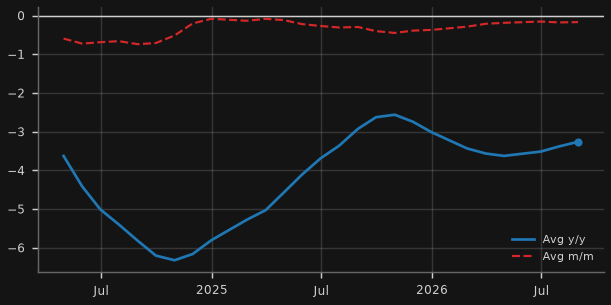
Why it matters for Australia: Falling prices erode household wealth and developer collateral, the core of China's credit drag.
Rule: Stress < -3%; cooling -3% to 0; steady 0 to +3%; heating > +3%.
Caveat: Simple average across cities of NBS Table I indices (computed here; NBS does not publish a national average).
Source: China NBS English press releases (scraped): 70 city table I (new commercial residential)
Activity
NBS manufacturing PMISTEADY
50.1 -0.2 over 3m
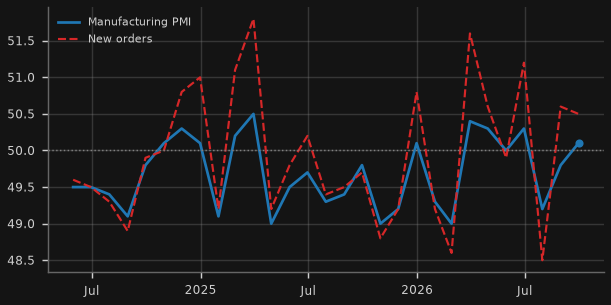
Why it matters for Australia: Factory momentum = steel, copper and energy demand from Australia's largest customer.
Rule: Heating >= 50.5; cooling < 49.5; otherwise steady (50 = no change).
Caveat: Parsed from NBS English releases; history limited to ~2 years of press releases. Caixin/S&P PMI is proprietary (not used).
Source: China NBS English press releases (scraped): Manufacturing PMI, new orders, non-manufacturing PMI
50.2 +0.0 over 3m
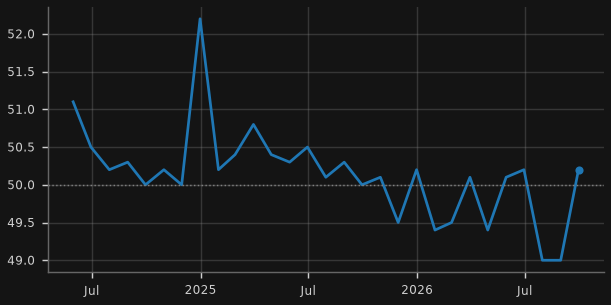
Why it matters for Australia: Services/construction activity: the domestic-demand side of China's rebalancing.
Rule: Heating >= 50.5; cooling < 49.5; otherwise steady (50 = no change).
Source: China NBS English press releases (scraped): Non-manufacturing business activity index
5.2% +0.7pp over 3m
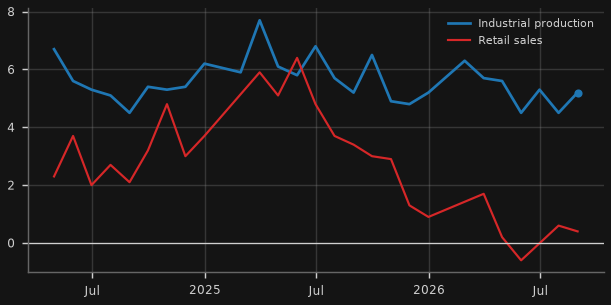
Why it matters for Australia: Supply (industry) vs demand (consumers): China's growth mix and its pull on Australian resources.
Rule: Industrial production y/y: heating > 6%; cooling < 4%; otherwise steady.
Caveat: Jan/Feb combined by NBS (no January print).
Source: China NBS English press releases (scraped): Industrial production, retail sales releases
Exports (US$, 3-mo y/y)HEATING
25.2% +13.3pp over 3m
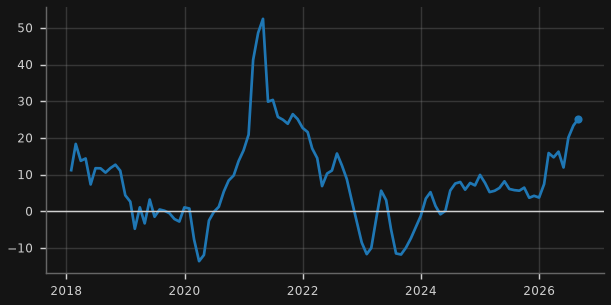
Why it matters for Australia: Export strength props up Chinese industry (and steel demand) while property is weak.
Rule: 3-month sum of USD exports, y/y: heating > +10%; cooling < 0%; otherwise steady.
Caveat: Verified vs China GAC: Aug-2026 exports US$401.44bn, +25.0% y/y in USD terms (+18.6% in CNY).
Source: OECD Data Explorer (DSD_IMTS@DF_IMTS): CHN.W.X.C.M.USD_EXC.N.N
Prices
CPI (y/y)STEADY
0.8% -0.4pp over 3m
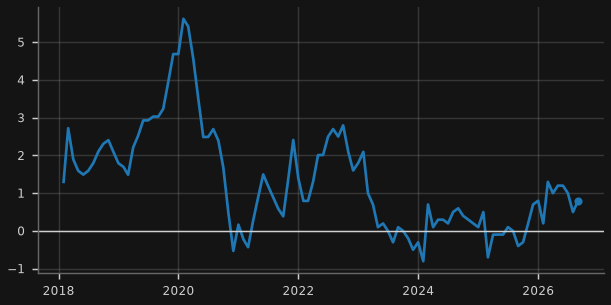
Why it matters for Australia: Low Chinese inflation exports disinflation (cheap goods) to Australia but signals weak domestic demand.
Rule: Cooling if < 0% (deflation); heating if > 2.5%; otherwise steady.
Caveat: BIS series with NBS release values where more recent.
Source: BIS Data Portal (WS_LONG_CPI): M.CN.771; China NBS English press releases (scraped): CPI release
Producer prices (y/y)HEATING
3.8% -0.1pp over 3m
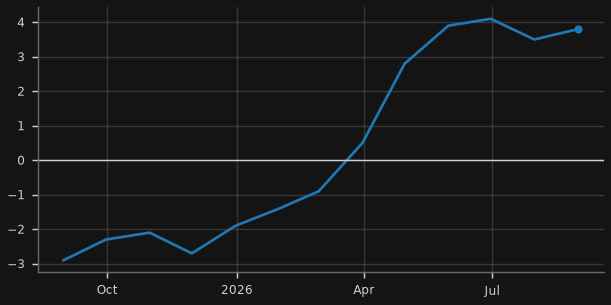
Why it matters for Australia: PPI tracks industrial pricing power; it moves with iron ore and coal prices.
Rule: Heating > +2%; cooling < -1%; otherwise steady.
Caveat: Only releases from Aug-2025 parse cleanly from NBS text (short history).
Source: China NBS English press releases (scraped): PPI release
Markets
1.69% -15bp over 1y
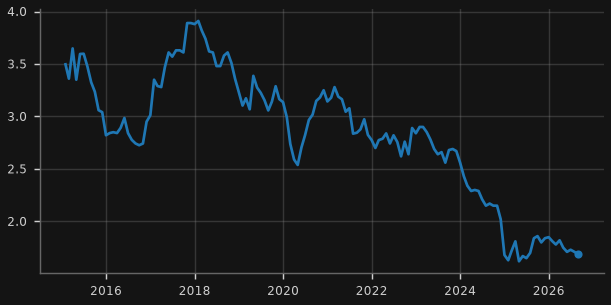
Why it matters for Australia: Record-low CGB yields signal deflationary pressure and weak credit demand.
Rule: 12-month change: cooling if <= -0.4pp; heating if >= +0.4pp; otherwise steady.
Caveat: Monthly average via OECD (lags ~1-2 months).
Source: OECD Data Explorer (DSD_STES@DF_FINMARK): CHN.M.IRLT.PA.....
USD/CNYSTEADY
6.6959 CNY -1.1% over 3m
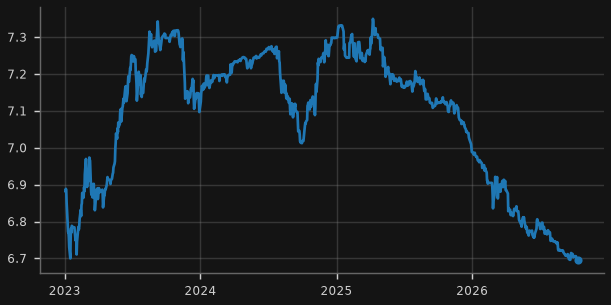
Why it matters for Australia: A weaker yuan exports deflation and usually coincides with softer commodity demand.
Rule: 3-month change: stress if CNY weakens > 3%; heating if CNY strengthens > 3%; otherwise steady.
Caveat: Cross rate derived from RBA 4pm AEST AUD rates.
Source: RBA table F11.1: FXRCR / FXRUSD (cross)
8,169 -1.8% over 3m
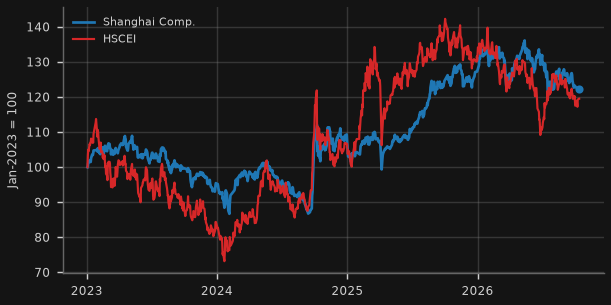
Why it matters for Australia: Chinese equity stress tends to spill into the AUD and Australian miners.
Rule: HSCEI: stress if >= 20% below 52-week high; cooling if 10-20% below; heating if within 2% of the 52-week high; otherwise steady.
Source: Yahoo Finance chart endpoint (unofficial): 000001.SS, ^HSCE
Japan
2heating 7steady 0cooling 1stress
Rates & yen
BoJ policy rateHEATING
1.25% +0.8pp over 1y
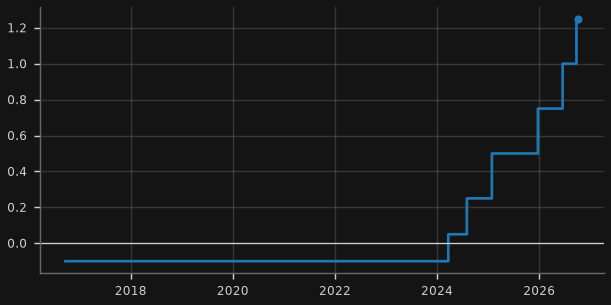
Why it matters for Australia: Each BoJ hike raises the cost of yen funding, the world's cheapest carry-trade leg.
Rule: 12-month change: heating (tightening) if >= +0.25pp; cooling (easing) if <= -0.25pp; otherwise steady.
Source: BIS Data Portal (WS_CBPOL): D.JP
JGB 2y & 10y yieldsHEATING
3.027% +27bp over 3m
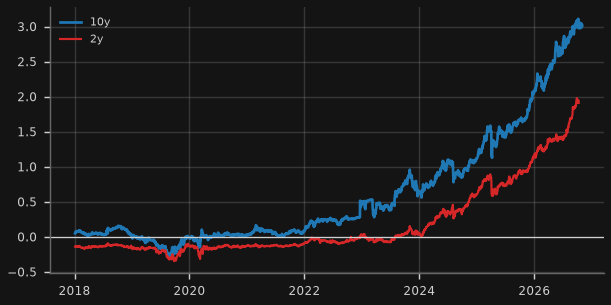
Why it matters for Australia: Higher JGB yields pull Japanese savings home, removing a big buyer of Australian and global bonds.
Rule: 10y, 3-month change: heating if >= +20bp; cooling if <= -20bp; otherwise steady.
Source: Japan MOF JGB interest rates: jgbcme_all.csv + jgbcme.csv
JGB 30y yieldSTEADY
4.085% +15bp over 3m
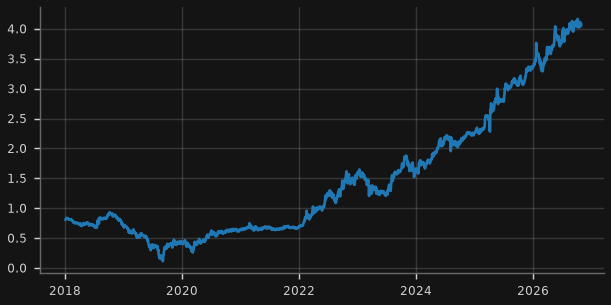
Why it matters for Australia: Super-long JGBs are where fiscal/term-premium stress shows; spikes have hit global duration.
Rule: Stress if 1-month change >= +40bp; heating if 3-month change >= +25bp; cooling if 3-month change <= -25bp; otherwise steady.
Source: Japan MOF JGB interest rates: jgbcme_all.csv + jgbcme.csv
USD/JPYSTEADY
158.27 JPY +2.0% over 1m
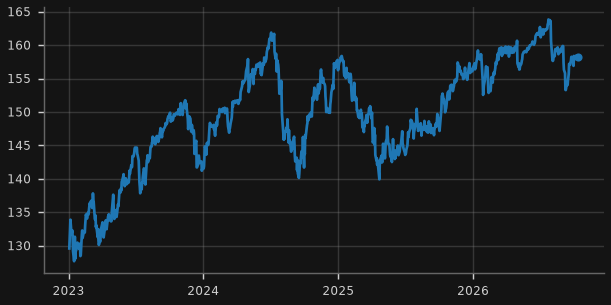
Why it matters for Australia: A sharp yen rally signals carry-trade unwinding, which has historically hit AUD and risk assets together.
Rule: Stress if yen strengthens >= 5% in 1 month (USD/JPY falls >= 5%); heating if yen weakens >= 5% over 3 months (carry building); otherwise steady.
Caveat: Cross rate derived from RBA 4pm AEST AUD rates.
Source: RBA table F11.1: FXRJY / FXRUSD (cross)
AUD/JPYSTEADY
110.17 JPY -0.5% over 1m
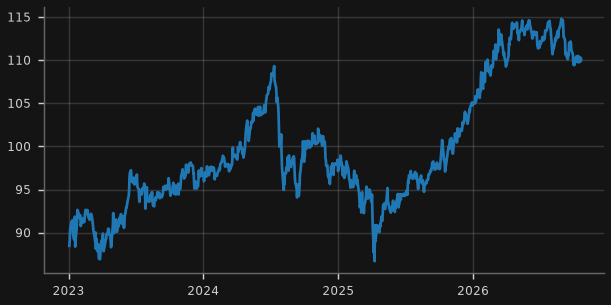
Why it matters for Australia: AUD/JPY is the purest carry-trade gauge for Australia: high-yielder vs funder.
Rule: Stress if 1-month change <= -5%; heating if 3-month change >= +5%; otherwise steady.
Source: RBA table F11.1: FXRJY
Economy & flows
Japan CPI (y/y)STEADY
1.9% +0.6pp over 3m
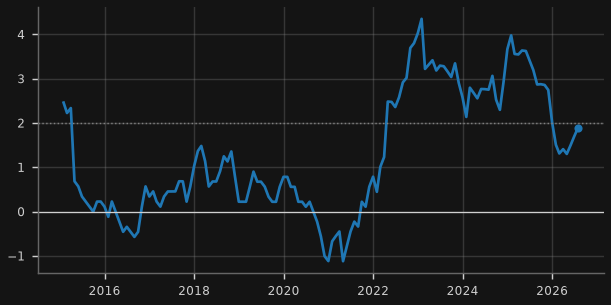
Why it matters for Australia: Sustained inflation is what lets the BoJ keep hiking (and JGB yields keep rising).
Rule: Heating > 2.5%; cooling < 1.5%; otherwise steady.
Caveat: BIS headline CPI (OECD/FRED Japan CPI series are stale); wages/shunto data need e-Stat API key (not used).
Source: BIS Data Portal (WS_LONG_CPI): M.JP.771
-1.8 ¥tn latest week -0.35tn
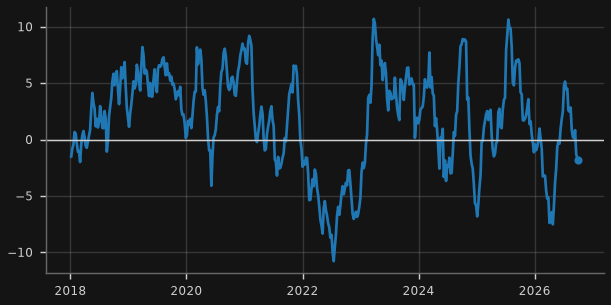
Why it matters for Australia: Japanese investors are major holders of Australian and US bonds; repatriation lifts global yields.
Rule: Percentile of trailing 10 years: stress <= 10th (heavy repatriation); heating >= 90th (heavy foreign buying); otherwise steady.
Caveat: Weekly designated-investor reports (MOF); sum of 13 weeks; units ¥ trillion (source 100m yen).
Source: Japan MOF International Transactions in Securities (weekly): week.csv
-3.2 ¥tn latest week equities +2.19tn
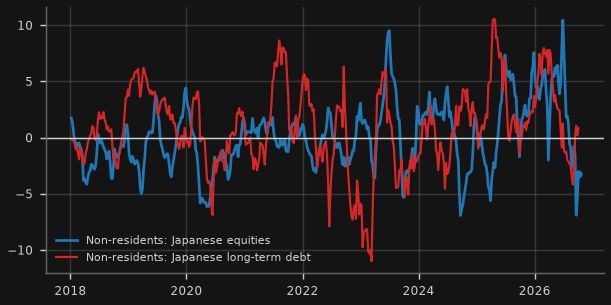
Why it matters for Australia: Foreign flows into Japan are a read on global risk appetite towards Asia.
Rule: Equities, percentile of trailing 10 years: stress <= 10th; heating >= 90th; otherwise steady.
Source: Japan MOF International Transactions in Securities (weekly): week.csv
Nikkei 225STEADY
67,702 +1.3% over 3m
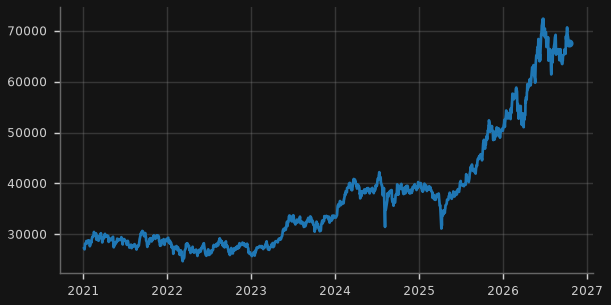
Why it matters for Australia: Japanese equity drawdowns often coincide with yen-carry unwinds.
Rule: Nikkei 225: stress if >= 20% below 52-week high; cooling if 10-20% below; heating if within 2% of the 52-week high; otherwise steady.
Source: Yahoo Finance chart endpoint (unofficial): ^N225
9.8% +4.6pp over 3m
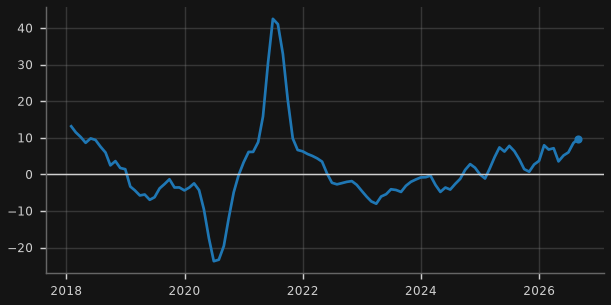
Why it matters for Australia: Japanese exports track the Asian manufacturing cycle that Australian LNG and coal feed.
Rule: 3-month sum of USD exports, y/y: heating > +10%; cooling < 0%; otherwise steady.
Source: OECD Data Explorer (DSD_IMTS@DF_IMTS): JPN.W.X.C.M.USD_EXC.N.N
US & global credit
7heating 12steady 3cooling 0stress
US rates, dollar & funding
FF 3.88%, real +0.62pp -0.9pp over 1y
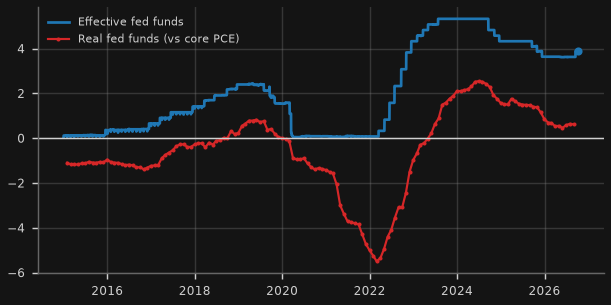
Why it matters for Australia: The Fed sets the global price of money; a high real Fed funds rate is the anchor for real rates everywhere, including Australia.
Rule: Real fed funds (monthly avg effective rate minus core PCE y/y): cooling (restrictive) if > 1.5pp; heating (stimulatory) if < 0; otherwise steady.
Caveat: Real rate observed only in months where core PCE is published (no interpolation).
Source: FRED (St Louis Fed): DFF; FRED (St Louis Fed): PCEPILFE
US Treasury 2y & 10yHEATING
5.22% +66bp over 3m
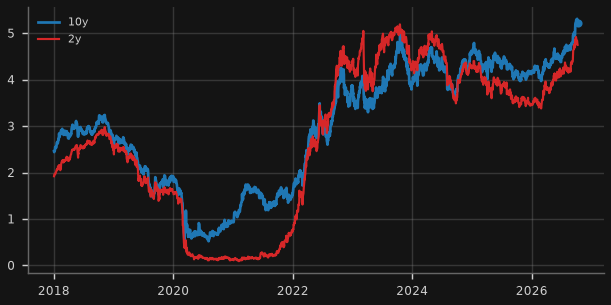
Why it matters for Australia: The 10y Treasury anchors global mortgage and corporate funding costs, including Australia's 10y.
Rule: 10y, 3-month change: heating (tightening) if >= +40bp; cooling if <= -40bp; otherwise steady.
Source: FRED (St Louis Fed): DGS10, DGS2
+0.44 pp +9bp over 3m
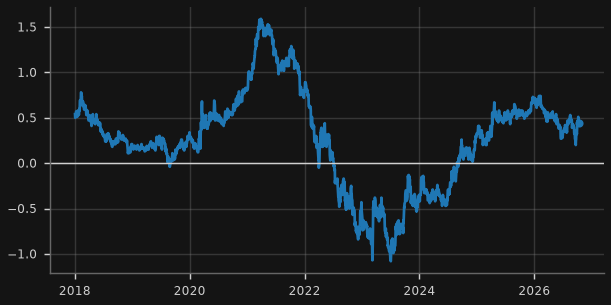
Why it matters for Australia: Curve shape signals whether markets see the Fed as too tight (inverted) or expect growth/inflation and term premium (steep).
Rule: Cooling if inverted (< 0); heating if > 1.25pp (steep); otherwise steady.
Source: FRED (St Louis Fed): T10Y2Y
2.87% +55bp over 3m
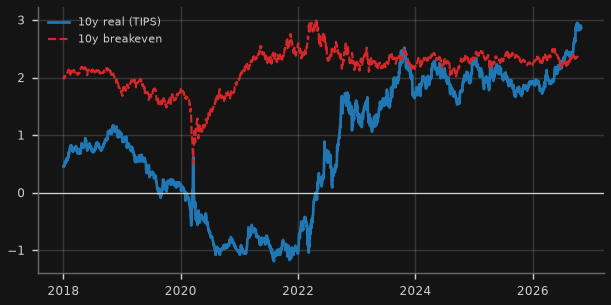
Why it matters for Australia: The global real rate: the hurdle every leveraged asset must clear, from US private credit to Australian property.
Rule: Cooling (restrictive) if > 2%; heating if < 1%; otherwise steady.
Source: FRED (St Louis Fed): DFII10, T10YIE
121.4 +0.6% over 3m
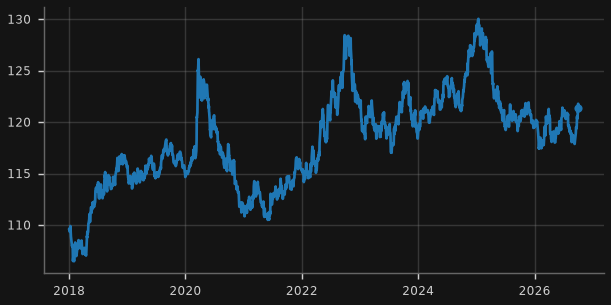
Why it matters for Australia: A rising dollar tightens financial conditions for Asian USD borrowers and pressures the AUD.
Rule: 3-month change: stress if >= +3% (dollar squeeze); heating (easy) if <= -3%; otherwise steady.
Source: FRED (St Louis Fed): DTWEXBGS
-3 bp +7bp over 3m
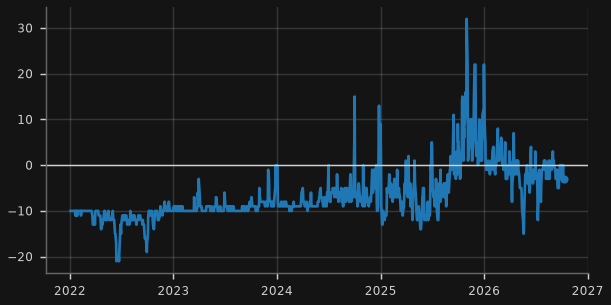
Why it matters for Australia: Repo stress (SOFR above interest on reserves) means dollar liquidity is getting scarce, which hits offshore USD borrowers and carry trades first.
Rule: 5-day average: stress if > +5bp (repo trading above IORB = reserve scarcity); cooling if > 0bp; otherwise steady.
Caveat: Month/quarter-end spikes are normal; rule uses a 5-day average.
Source: FRED (St Louis Fed): SOFR, IORB, RRPONTSYD
US & global credit conditions
3.15% +46bp over 3m
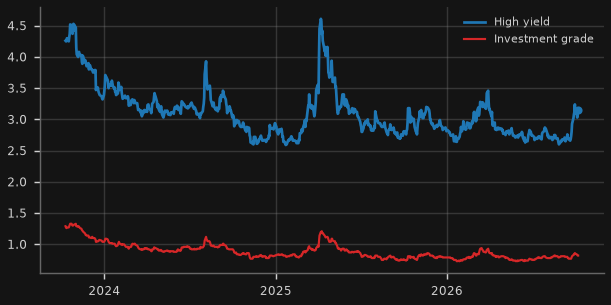
Why it matters for Australia: The bellwether of the global credit cycle; private credit marks lag but follow it.
Rule: HY OAS: stress > 6%; cooling 4.5-6%; heating < 3.5% (very easy credit); otherwise steady.
Caveat: ICE BofA indices via FRED (FRED serves a rolling window of history only).
Source: FRED (St Louis Fed): BAMLH0A0HYM2, BAMLC0A0CM
0.91% +10bp over 3m
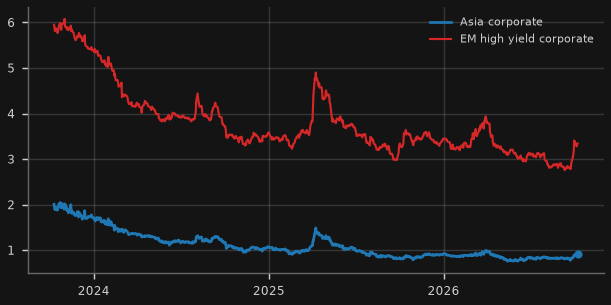
Why it matters for Australia: What Asian borrowers pay for dollar credit; widening hits Chinese developers and regional banks first.
Rule: Percentile of trailing 10 years: stress >= 90th; cooling 70-90th (credit tightening); heating <= 20th (very tight spreads = easy credit); otherwise steady. Applied to Asia corporate OAS.
Source: FRED (St Louis Fed): BAMLEMRACRPIASIAOAS, BAMLEMHBHYCRPIOAS
12.10 US$ -4.5% over 3m
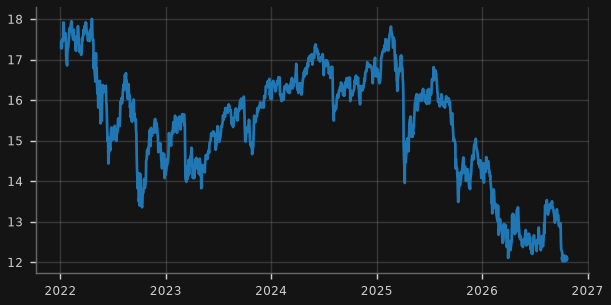
Why it matters for Australia: Listed BDCs are the daily-priced window into US direct lending; sell-offs here have led stress in Australian private-credit trusts.
Rule: BIZD price: stress if >= 20% below 52-week high; cooling if 10-20% below; heating if within 2% of the 52-week high; otherwise steady.
Caveat: Price only (excludes ~10%+ distribution yield); VanEck BDC Income ETF tracks MarketVector US Business Development Companies index.
Source: Yahoo Finance chart endpoint (unofficial): BIZD
-0.49 +0.0 over 3m
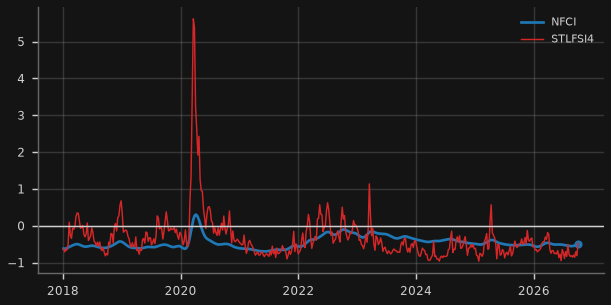
Why it matters for Australia: Broad US financial conditions; tightening here tends to transmit to Asian funding markets.
Rule: NFCI: stress > 0 (tighter than average); heating < -0.3 (loose); otherwise steady.
Source: FRED (St Louis Fed): NFCI, STLFSI4
VIXSTEADY
14.8 -1.0 over 1m
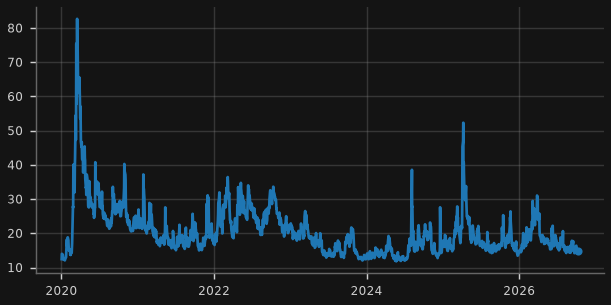
Why it matters for Australia: Volatility shocks force deleveraging across carry trades and risk assets, including the AUD.
Rule: Stress > 30; cooling 20-30; heating < 13; otherwise steady.
Source: FRED (St Louis Fed): VIXCLS
+0.0 net % -9.5 over 1y
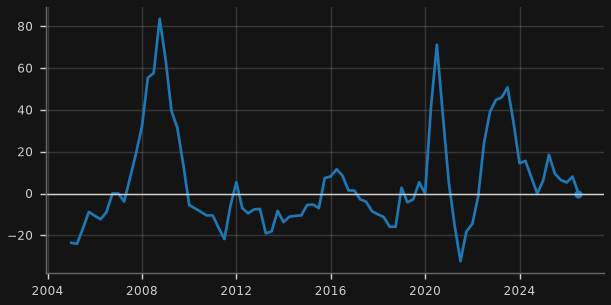
Why it matters for Australia: Bank credit supply leads defaults by ~a year; tightening pushes borrowers to private credit.
Rule: Stress > 20; cooling 0-20; heating < -10; otherwise steady.
Source: FRED (St Louis Fed): DRTSCILM
US bank C&I loans (y/y)COOLING
10.0% +13.1pp over 1y
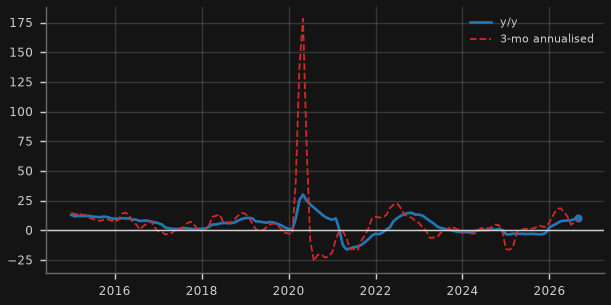
Why it matters for Australia: Bank business lending vs private credit: which channel is funding US corporates.
Rule: Heating if y/y > 10% or 3-mo annualised growth exceeds y/y by > 1pp (accelerating); cooling if 3-mo annualised is > 1pp below y/y (decelerating); otherwise steady.
Source: FRED (St Louis Fed): BUSLOANS
US economy
3.0% -0.2pp over 3m
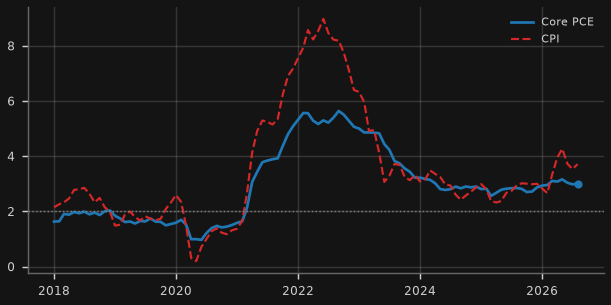
Why it matters for Australia: US inflation decides how far the Fed can cut (or must hike), and so the global floor under real rates.
Rule: Core PCE: heating > 3%; cooling < 2%; otherwise steady.
Source: FRED (St Louis Fed): PCEPILFE, CPIAUCSL
4.2% -0.2pp over 1y
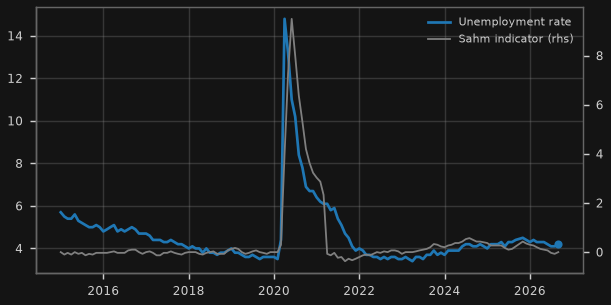
Why it matters for Australia: A rising US jobless rate is the classic trigger for a global easing cycle and risk-off.
Rule: Stress if 3-mo avg >= 0.5pp above its low of the prior 12 months (Sahm-style); else cooling if 3-mo avg up >= 0.2pp y/y; heating if down >= 0.2pp y/y; otherwise steady. The Fed's official real-time Sahm indicator (SAHMREALTIME, recession signal >= 0.50) is shown for reference.
Source: FRED (St Louis Fed): UNRATE, SAHMREALTIME
198 '000 -15.4% over 1y
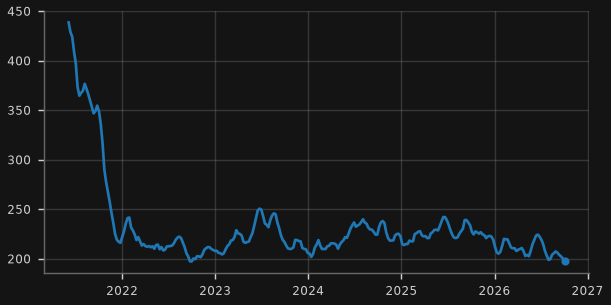
Why it matters for Australia: Weekly, real-time read on US layoffs.
Rule: 4-wk average y/y: stress >= +20%; cooling >= +10%; heating <= -10%; otherwise steady.
Source: FRED (St Louis Fed): ICSA
6.75 US$tn +2.4% over 1y
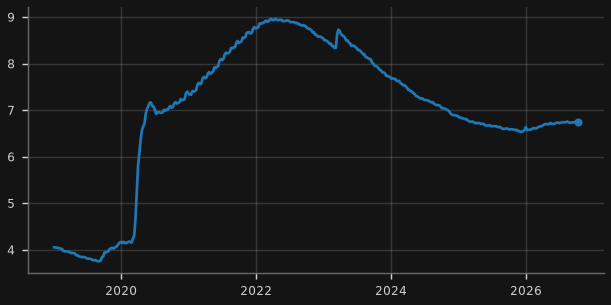
Why it matters for Australia: QT drains dollar liquidity that ultimately funds global carry and credit.
Rule: y/y: cooling (QT) if < -5%; heating (QE) if > +5%; otherwise steady.
Source: FRED (St Louis Fed): WALCL
Brent crude (US$/bbl)HEATING
125.4 US$ +87.0% over 1y
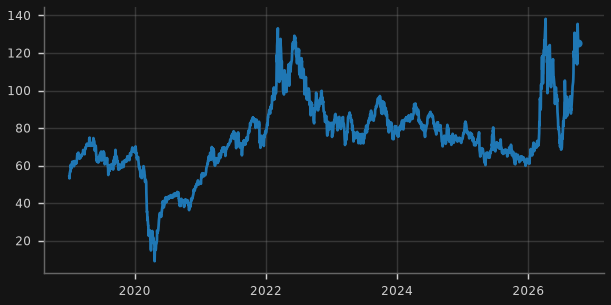
Why it matters for Australia: Oil drives Australian fuel inflation and Asia's import bill (most of Asia is a net oil importer); LNG contracts are oil-linked.
Rule: y/y: heating > +20%; cooling < -20%; otherwise steady.
Caveat: EIA Brent spot (physical, dated) via FRED, lags a few days. In Oct-2026 physical Dated Brent (~US$129 on 7 Oct) traded ~US$28 above ICE front-month futures (~US$100) because of Hormuz disruption, so headline futures quotes look much lower.
Source: FRED (St Louis Fed): DCOILBRENTEU
Global credit cycle (BIS)
7.3% +2.1pp over 1y
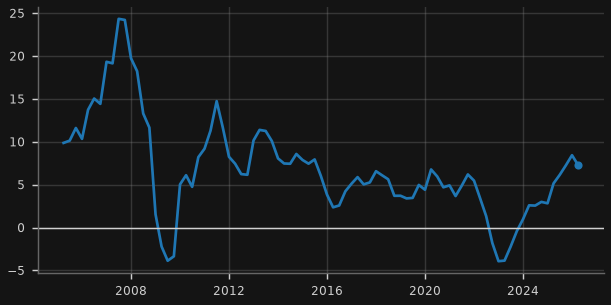
Why it matters for Australia: The offshore dollar credit cycle: Asian corporates and sovereigns are among the biggest users.
Rule: Heating > 8%; cooling < 0%; otherwise steady.
Source: BIS Data Portal (WS_GLI): Q.USD.3P.N.A.I.B.771
Credit-to-GDP gaps (BIS, pp)HEATING
-9.7 pp +3.8pp over 1y
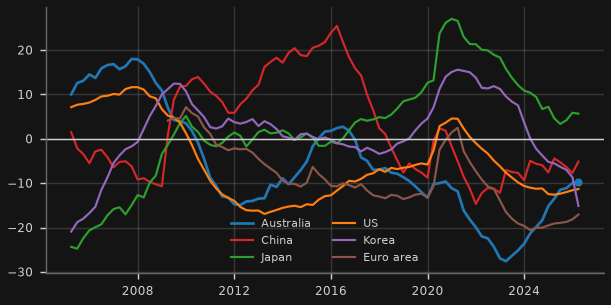
Why it matters for Australia: Credit far above trend has preceded most banking crises; a negative gap means deleveraging.
Rule: Per economy: stress > +10pp; heating +2 to +10; steady -2 to +2; cooling < -2. Status shown is for the highest gap.
Caveat: Latest value field shows Australia; the gap is a one-sided HP-filter trend and is unreliable for China/Japan structural shifts.
Source: BIS Data Portal (WS_CREDIT_GAP): Q.AU+CN+JP+US+KR+XM.P.A.C
20.3% -0.3pp over 1y
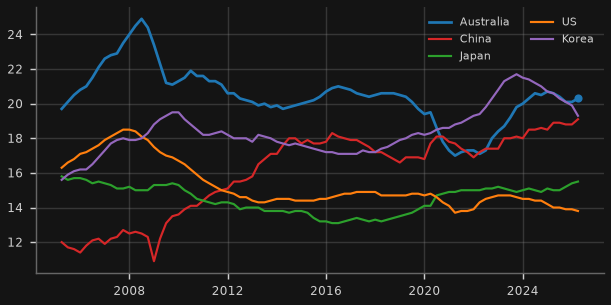
Why it matters for Australia: Direct test of the thesis: the share of income going to interest and principal.
Rule: Australia vs its own 10-year average: stress >= +2pp; cooling (restrictive) >= +1pp; heating <= -1pp; otherwise steady.
Source: BIS Data Portal (WS_DSR): Q.AU+CN+JP+US+KR.P
0.2 % GDP -2.2 over 1y
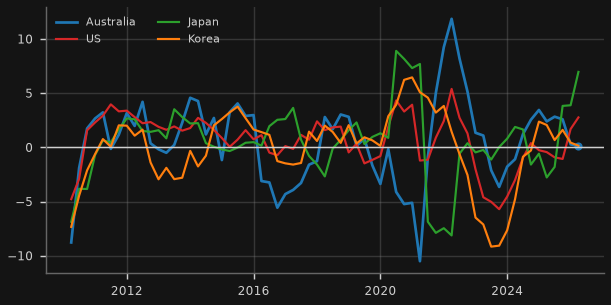
Why it matters for Australia: A positive impulse adds to demand growth; Australia's is driven by housing and business credit.
Rule: 4-quarter change in 4-quarter credit flow as % of GDP: heating > +1pp; cooling < -1pp; otherwise steady. Applied to Australia.
Caveat: Derived from BIS total credit to private non-financial sector (all lenders, market value).
Source: BIS Data Portal (WS_TC): Q.AU+US+JP+KR.P.A.M.XDC+770.A
4.2% +2.2pp over 1y
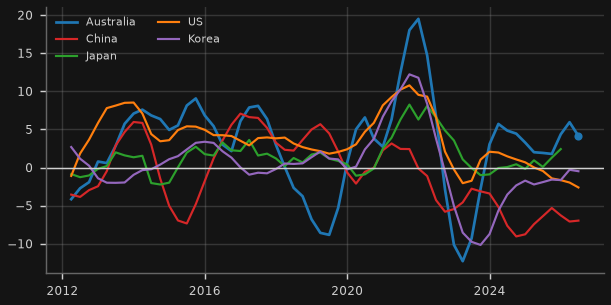
Why it matters for Australia: Property is the main collateral for credit across the region.
Rule: Context only (no traffic light).
Caveat: CPI-deflated; coverage differs by country (China = 70-city new homes).
Source: BIS Data Portal (WS_SPP): Q.AU+CN+JP+US+KR.R.771
Funding & liquidity
2heating 6steady 0cooling 0stress
Live US dollar funding and curve indicators from the NY Fed, Federal Reserve and FRED: repo rates vs interest on reserves, primary-dealer settlement fails, Fed backstop facilities, the near-term forward spread, curve slopes and the copper/gold ratio.
Repo & Fed backstops
-3 bp +7bp over 3m
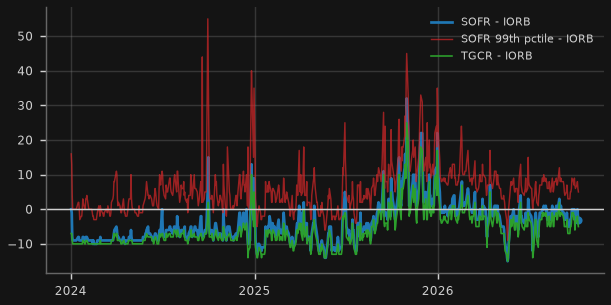
Why it matters for Australia: Repo trading at or above interest on reserves means dealers are balance-sheet constrained and dollar liquidity is getting scarce; the 99th percentile shows the tail of the market paying up first.
Rule: 5-day avg SOFR-IORB: stress if > +5bp; heating if > 0bp or SOFR 99th pctile 5-day avg > +10bp; otherwise steady.
Caveat: Month/quarter-end spikes are normal (rule uses 5-day averages). BGCR and TGCR differ by ~0-1bp; TGCR shown. IORB starts Jul-2021.
Source: NY Fed Markets API (SOFR, BGCR, TGCR): rate, 1st/99th percentile, volume; FRED (St Louis Fed): IORB
2,963 US$bn +1.3% over 1y
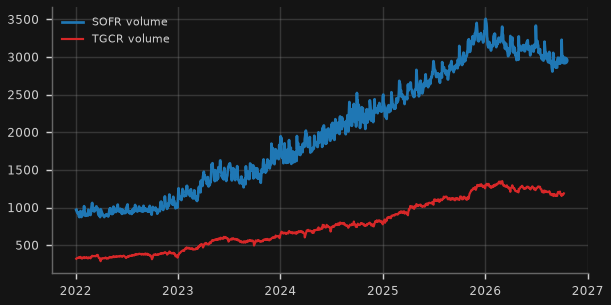
Why it matters for Australia: Rising repo volume with flat rates = ample collateral financing; rising rates with flat or falling volume would point to balance-sheet scarcity.
Rule: Context only (no traffic light).
Source: NY Fed Markets API (SOFR, TGCR): volumeInBillions
260.0 US$bn -18.8% over 1y
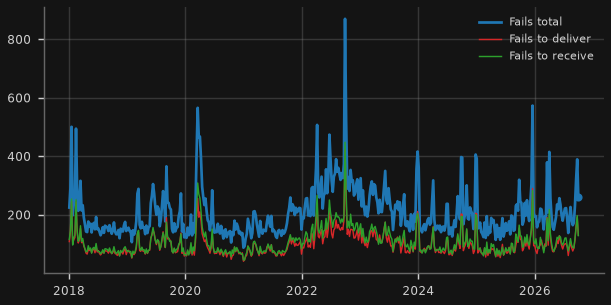
Why it matters for Australia: Settlement fails jump when Treasuries are hard to borrow (collateral scarcity, e.g. Mar-2020); persistent spikes can impair repo intermediation and dollar funding.
Rule: 4-week average vs trailing 3-year median: stress if > 2x; heating if > 1.3x; otherwise steady.
Caveat: Weekly cumulative fails reported by primary dealers (Wednesday as-of dates); this API series starts Apr-2013 (older history uses a different series layout).
Source: NY Fed Markets API (Primary dealer statistics): PDFTD-USTET, PDFTR-USTET (US$m, weekly, cumulative for the week)
0.0 US$bn +0.0 over 3m
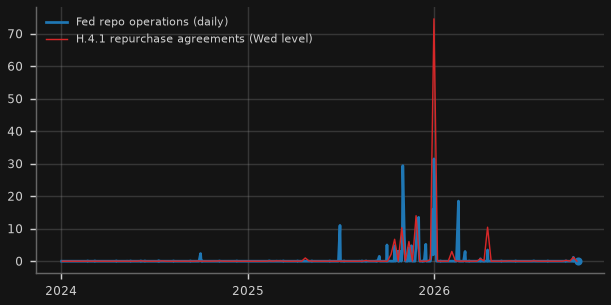
Why it matters for Australia: Use of the Fed's repo backstop shows dealers cannot get private repo at a reasonable price, an early sign of funding strain that spills over to offshore dollar borrowers.
Rule: Max over last 20 business days: stress if >= US$50bn; heating if >= US$5bn; otherwise steady.
Caveat: Quarter-end takeup (e.g. 30 Sep) is common and partly window-dressing; the rule looks at the 20-day max, so a quarter-end print alone can trigger 'heating'.
Source: FRED (St Louis Fed): RPONTSYD, WORAL
0.21 US$bn +0.2 over 1y
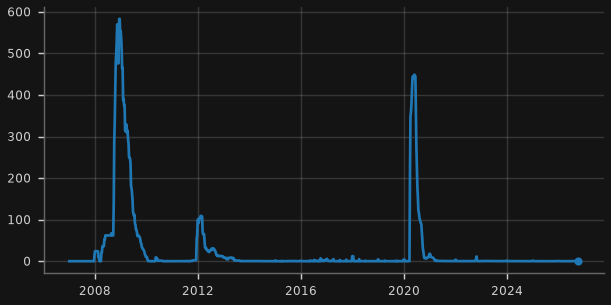
Why it matters for Australia: Swap-line drawings are the clearest sign of an offshore dollar shortage: foreign central banks borrow US dollars from the Fed to lend on to their banks.
Rule: Latest: stress if >= US$50bn; heating if >= US$5bn; otherwise steady.
Source: FRED (St Louis Fed): SWPT
9.96 US$bn +2.8 over 1y
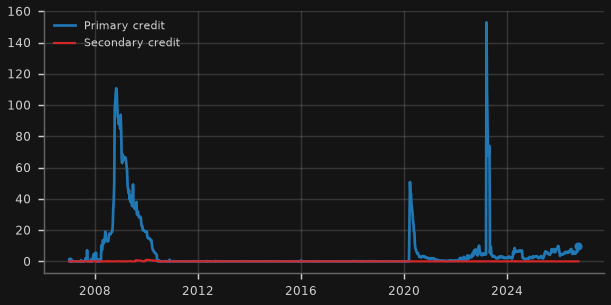
Why it matters for Australia: Banks only borrow at the discount window when market funding fails or stigma is outweighed; spikes mark bank funding stress (2008, 2020, Mar-2023).
Rule: Primary credit: stress if >= US$25bn; heating if >= 2x its 3-year median; otherwise steady.
Caveat: Wednesday levels. Seasonal credit (WLCFLSECL) excluded.
Source: FRED (St Louis Fed): WLCFLPCL, WLCFLSCL
0.0 US$bn
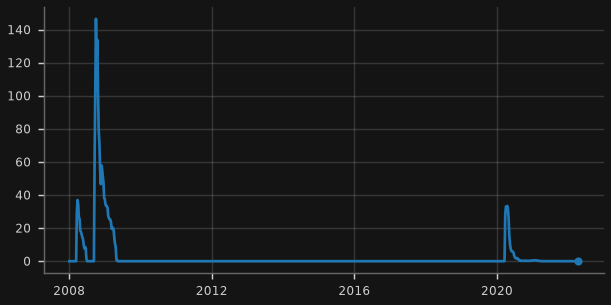
Why it matters for Australia: The PDCF is the Fed lending directly to securities dealers; it was only used in 2008 and 2020 and is shown for history.
Rule: Context only (no traffic light).
Caveat: Spliced from the 2008-era series and the 2020-22 facility series; both discontinued, so this card is history only.
Source: FRED (St Louis Fed): H0RESPPALDDNWW, H41RESPPALDHNWW
Curve & forward signals
+97 bp +66bp over 3m
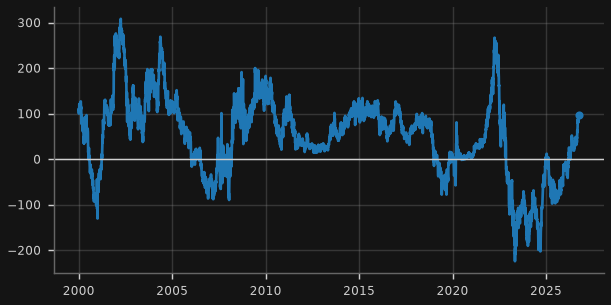
Why it matters for Australia: The Fed's own preferred curve recession signal (Engstrom-Sharpe): a negative spread means markets price rate cuts within 18 months, i.e. expected weakness.
Rule: Latest 5-day avg: cooling if < 0bp (cuts priced = recession signal); heating if > +100bp; otherwise steady.
Caveat: Computed here: forward = Svensson zero curve 1.5y-1.75y (converted to quarterly compounding) minus 3m CMT bill (DGS3MO). The Fed's published series uses its own bill-curve fit, so levels differ by a few bp. GSW lags ~1 week.
Source: Federal Reserve GSW zero-coupon curve (feds200628): BETA0-3, TAU1-2 -> Svensson zero yields at 1.5y and 1.75y; FRED (St Louis Fed): DGS3MO
+0.99 pp +28bp over 3m
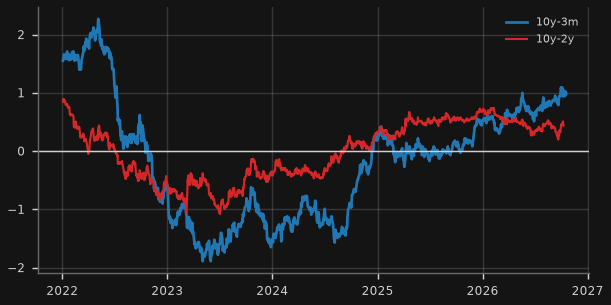
Why it matters for Australia: Curve inversion and the later bull steepening have preceded US recessions; a steep curve with rising long yields can instead reflect term or policy-risk premia.
Rule: 10y-3m: cooling if < 0 (inverted); otherwise steady.
Source: FRED (St Louis Fed): T10Y3M, T10Y2Y
1.60 ratio +30.0% over 1y
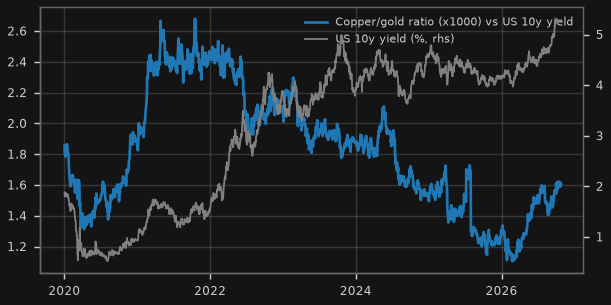
Why it matters for Australia: Copper (industrial demand) relative to gold (safety, liquidity) tends to track long-term yields; divergence tests whether higher yields reflect growth or other forces.
Rule: 3-month change: cooling if <= -10%; heating if >= +10%; otherwise steady.
Caveat: Front-month COMEX futures (US$/lb over US$/oz). Copper was supply-constrained in 2026, which lifts the ratio without implying stronger growth.
Source: Yahoo Finance chart endpoint (unofficial): HG=F; Yahoo Finance chart endpoint (unofficial): GC=F; FRED (St Louis Fed): DGS10
Asia region
4heating 2steady 1cooling 0stress
Trade & tech cycle
67.5% +17.1pp over 3m
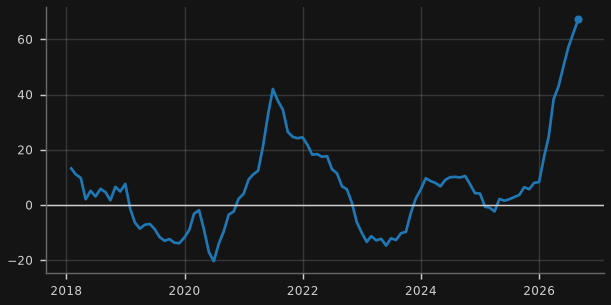
Why it matters for Australia: Korea is the canary for Asian trade and the semiconductor cycle.
Rule: 3-month sum of USD exports, y/y: heating > +10%; cooling < 0%; otherwise steady.
Caveat: Verified vs MOTIR: Aug-2026 US$98.25bn, +68.7% y/y (semiconductors +209%). Sep-2026 (US$120.9bn, +83.5%) not yet in OECD feed. Customs 10/20-day data not available via free API.
Source: OECD Data Explorer (DSD_IMTS@DF_IMTS): KOR.W.X.C.M.USD_EXC.N.N
27.1% +12.3pp over 3m
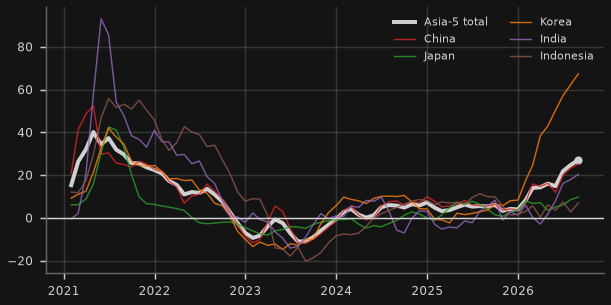
Why it matters for Australia: Regional export momentum = demand for Australian energy, metals and services.
Rule: 3-month sum of USD exports, y/y: heating > +10%; cooling < 0%; otherwise steady. Aggregate of China, Japan, Korea, India, Indonesia (months where all five report).
Caveat: Taiwan and Vietnam are not in OECD IMTS (Taiwan customs has no free bulk API); aggregate stops at the latest month all five report.
Source: OECD Data Explorer (DSD_IMTS@DF_IMTS): CHN+JPN+KOR+IND+IDN.W.X.C.M.USD_EXC.N.N
48,341 +79.6% over 1y
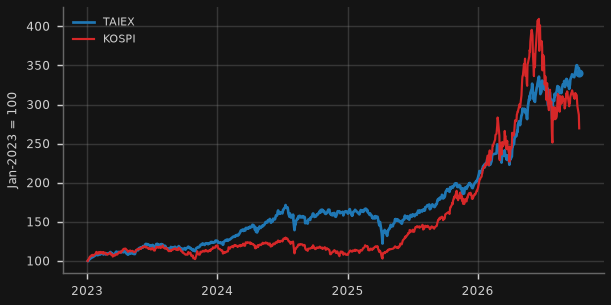
Why it matters for Australia: Taiwan/Korea equities are dominated by chipmakers: the AI/semis cycle drives Asian capex and trade.
Rule: TAIEX: stress if >= 20% below 52-week high; heating if 12-month return > +25%; cooling if < -10%; otherwise steady.
Caveat: Proxy for Taiwan exports/semis billings (no free keyless source found). Verified: TAIEX record close 49,822.55 on 7 Oct 2026, about +70-72% YTD; KOSPI about +60-65% YTD.
Source: Yahoo Finance chart endpoint (unofficial): ^TWII, ^KS11
99.81 +0.0 over 3m
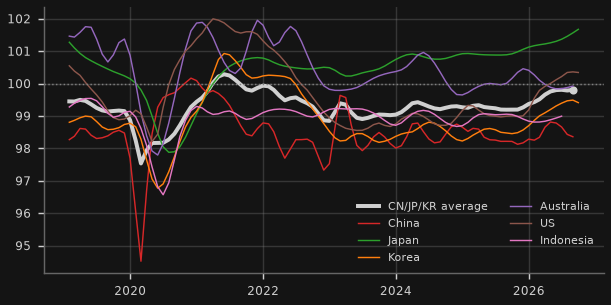
Why it matters for Australia: Free proxy for regional PMIs: manufacturing confidence across Australia's main customers.
Rule: Average of China, Japan, Korea (months all report): heating > 100.5; cooling < 99.5; otherwise steady (100 = long-run average).
Caveat: S&P Global / Caixin PMIs are proprietary. OECD BCI is amplitude-adjusted (100 = long-term average). India's series ends Feb-2026 (excluded).
Source: OECD Data Explorer (DSD_STES@DF_CLI): CHN+JPN+KOR+IDN+AUS+USA.M.BCICP...AA...H
FX, rates & prices
95.6 +1.3% over 3m
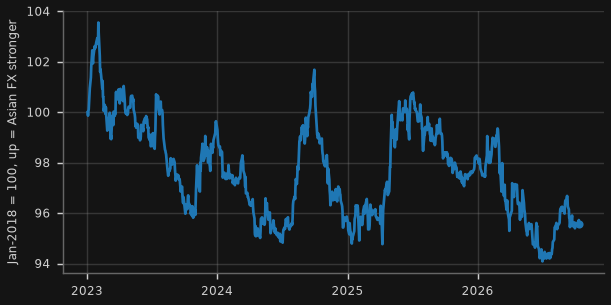
Why it matters for Australia: Asian currency weakness signals dollar funding stress and capital outflow in the region.
Rule: 3-month change: stress if Asian FX weakens >= 3%; heating if it strengthens >= 3%; otherwise steady.
Caveat: Built from RBA AUD cross rates (KRW, TWD, INR, IDR, SGD, THB, MYR, PHP); excludes CNY and JPY (own sections).
Source: RBA table F11.1: FXRSKW, FXRNTD, FXRIRE, FXRIR, FXRSD, FXRTB, FXRMR, FXRPHP (crossed with FXRUSD)
3.00% +50bp over 6m
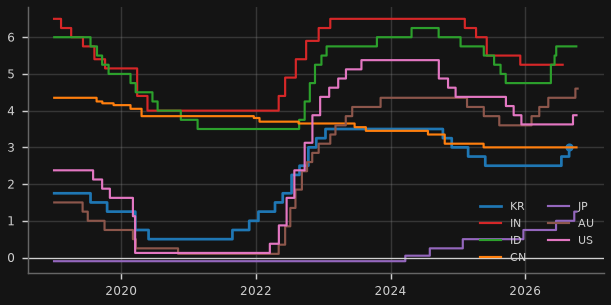
Why it matters for Australia: Regional easing vs tightening shows whether Asia is fighting slowdown or inflation/currency pressure.
Rule: Count of the 7 central banks that moved >= 10bp over 6 months: cooling (easing cycle) if cuts exceed hikes by >= 3; heating if hikes exceed cuts by >= 3; otherwise steady.
Caveat: Latest value field shows Korea. BIS series except Australia (RBA F1 cash rate target, fresher than BIS). China as defined by BIS; US = midpoint of target range.
Source: BIS Data Portal (WS_CBPOL): D.KR+IN+ID+CN+JP+US; RBA table F1: FIRMMCRTD
4.4% +1.0pp over 3m
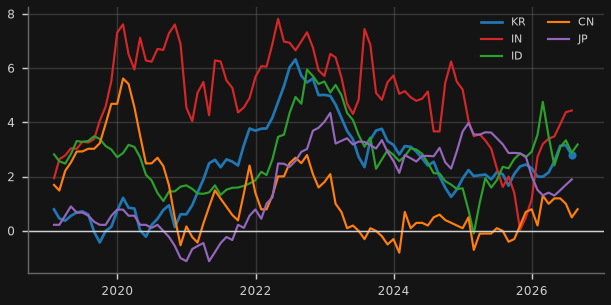
Why it matters for Australia: Inflation differentials drive where regional rates (and currencies) head.
Rule: Context only (no traffic light).
Caveat: Latest value field shows India.
Source: BIS Data Portal (WS_LONG_CPI): M.KR+IN+ID+CN+JP.771
4.45% +160bp over 1y
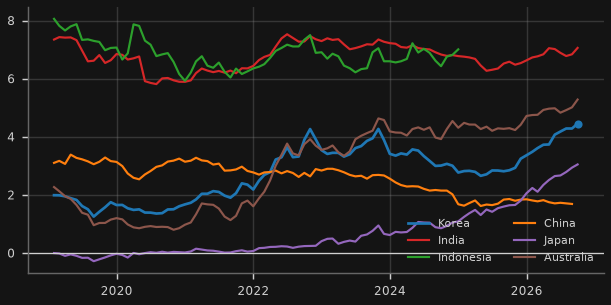
Why it matters for Australia: Australia's 10y now sits above most of Asia: relative yields drive regional demand for AUD bonds.
Rule: Context only (no traffic light).
Caveat: Latest value field shows Korea. Indonesia not available in OECD feed.
Source: OECD Data Explorer (DSD_STES@DF_FINMARK): CHN+IND+IDN+JPN+KOR+AUS.M.IRLT.PA.....
Hang Seng IndexCOOLING
24,295 -2.9% over 3m
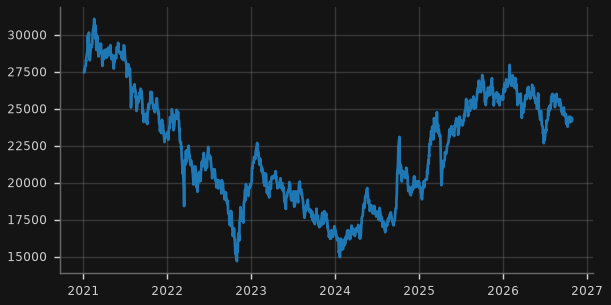
Why it matters for Australia: Hong Kong is the offshore market for Chinese risk; its drawdowns mark regional risk-off.
Rule: Hang Seng: stress if >= 20% below 52-week high; cooling if 10-20% below; heating if within 2% of the 52-week high; otherwise steady.
Source: Yahoo Finance chart endpoint (unofficial): ^HSI
Geopolitics watch
Hand-curated, dated items, each checked against the linked source on 12 Oct 2026. These are qualitative and deliberately not scored; the GPR and EPU charts below are context only. Update geo.py ITEMS when refreshing.
| Date | Theme | What happened | Market channel to Australia/Asia | Source |
|---|---|---|---|---|
| 7-11 Oct 2026 | Middle East / energy shipping | Hormuz escalation moved to the bypass route: on 7 Oct Iran said it would close the 'illegal' southern route hugging Oman's coast, and a tanker was hit by 'multiple projectiles' off Qatar (~500km west of the strait). On 9-10 Oct the IRGC said it struck the LPG carrier NV Sunshine on that route, and UKMTO reported a projectile fire on the crude tanker GEM NO2 off the UAE. Trump said on 8 Oct the US will not attack Iran before the 3 Nov midterms. On 11 Oct Iran's security council head called the latest US response 'insufficient'. Brent futures settled US$104.72 on 9 Oct (US$100.20 on 7 Oct). | Brent and oil-linked Asian LNG prices; Australian fuel inflation and so the RBA; LNG export receipts; Asian importers' terms of trade | The Guardian, 8 Oct 2026 Asharq Al-Awsat / AFP, 10 Oct 2026 |
| 6-8 Oct 2026 | Middle East / energy shipping | Strait of Hormuz: tanker attacks hit their highest weekly level since the Iran war began (28 Feb 2026). Only seven commodity vessels transited on 6 Oct (lowest since 23 Jul), and crude through the strait fell to ~10.1 mb/d, 74% of pre-war (Kpler). Gulf exports rerouted via the Gulf of Oman and the Red Sea kept total Middle East crude exports near pre-war levels. | Brent and oil-linked Asian LNG prices; Australian fuel inflation (and so the RBA); LNG export receipts; Asian importers' terms of trade | The National / Reuters, 8 Oct 2026 |
| 10 Oct 2026 | Fuel security / Russia | Trump announced a deal for Russia to supply 300,000 tons of diesel to the US and global markets immediately, then 500,000 tons in November, rising later to 3m tons. Energy Minister Bowen said Australia does not 'need or want' Russian fuel and will not change its approach. Australia holds 43 days of petrol and 31 days of diesel, with 51 fuel ships en route and 3.2bn litres contracted over the next four weeks. | Global diesel supply and margins; Australian diesel and freight costs (CPI automotive fuel, and so the RBA); mining and farm input costs; friction with US sanctions policy | The Guardian, 10 Oct 2026 ABC News, 10 Oct 2026 |
| 27 Sep - 5 Oct 2026 | US-China trade | After Xi's 24-25 Sep state visit to Washington, the US and China released '30-for-30' Board of Trade lists: reciprocal tariff cuts (mostly to MFN) on ~US$30bn of goods each way. Officials say cuts are not immediate (US Section 301 notice-and-comment first). The Kuala Lumpur tariff truce was extended from 10 Nov 2026 to 10 Jan 2027. China's list includes US coal. | CNY, China export growth, iron ore sentiment, AUD; US coal gaining access to China competes with Australian coal | Covington, 5 Oct 2026 Caixin, 1 Oct 2026 |
| 8 Oct 2026 | China-Australia trade (iron ore) | Fortescue's September-quarter update: cash fell 37% to $3.2bn (from $5.1bn) and net debt rose to $2.8bn (from $0.9bn). Shipments were 46.8 Mt (-6% y/y, port maintenance) and sales 42.9 Mt. FY27 shipment, cost and capex guidance is held but 'subject to' negotiations with China's state buyer CMRG, which earlier this year told some mills not to take Fortescue's flagship product. BHP settled its own CMRG standoff in April 2026. | Iron ore pricing power shifting toward Chinese buyers; Pilbara volumes and margins; budget mining receipts; AUD | Mining Weekly / Reuters, 8 Oct 2026 |
| 9 Oct 2026 | Japan politics / BoJ | The Takaichi cabinet approved and submitted its bill to cut the consumption tax on food and drink from 8% to 1% for two years from April 2027, plus income-linked payments; ~¥10tn of revenue is lost over two years. The government says no deficit-financing bonds will be used but has not named funding sources (Diet session ends 12 Dec). The BoJ (1.25% after June and September hikes) is expected to hold at its 29-30 Oct meeting, and the Fed is expected to hike on 28 Oct (MUMSS view, 5 Oct). | JGB 10y/30y yields and term premium, yen carry (USD/JPY, AUD/JPY), Japanese demand for foreign bonds including AGS | Kyodo News, 9 Oct 2026 MUFG/MUMSS Japan Weekly, 5 Oct 2026 |
| 5 Oct 2026 | Japan-Australia economic security | Treasurer Chalmers and Finance Minister Katayama signed a memorandum in Tokyo setting up an annual Japan-Australia Finance Ministerial Dialogue. It covers sharing information on investment trends and supply chains (including defence industry), energy security and critical minerals. Japan's only similar finance dialogues are with Korea and China (the China one has not met since August 2018). | Japanese capital inflows into Australian resources, energy and infrastructure; LNG supply security for Japan; critical-minerals financing (e.g. Lynas) as a hedge against China's export controls | The Japan Times / Bloomberg, 6 Oct 2026 Japan Ministry of Finance, 5 Oct 2026 |
| 6-11 Oct 2026 | Taiwan Strait | In the 24 hours to 6am on 10 Oct, Taiwan's MND tracked 21 PLA aircraft sorties (13 crossed the median line), 7 PLAN ships and 2 official ships. This followed a 6 Oct 'joint combat readiness patrol' (14 sorties, 9 across the line). After President Lai's 10 Oct National Day address, Beijing's Taiwan Affairs Office called him a 'pragmatic worker for Taiwan independence'. | Risk premium on TAIEX/semis supply chain (TSMC is ~41% of the TAIEX); regional risk-off hits AUD and Asian FX | Taiwan MND, PLA activity 9-10 Oct 2026 (Chinese) Taiwan MND press release, 6 Oct 2026 People's Daily / Xinhua, 11 Oct 2026 |
| 1-9 Oct 2026 | South China Sea | USNI counts at least six dangerous Philippine-China encounters since 1 Oct (Scarborough, Second Thomas Shoal, Spratlys), plus a new front in the Luzon Strait near Batanes, where Taiwan's coast guard shadowed a Chinese survey ship and its escort. On 8 Oct China Coast Guard water cannon and blocking delayed a medical evacuation from BRP Sierra Madre at Second Thomas (Ayungin) Shoal by nearly 10 hours. On 9 Oct Philippine forces pushed a Chinese militia vessel and 22 small boats away from Loaita Island. On 3 Oct a J-16 intercepted a Philippine C-208 over Scarborough. | Shipping-lane risk on Australia's northern trade routes; regional defence spending; risk sentiment | USNI News, 9 Oct 2026 GMA News, 9 Oct 2026 |
| 25 Sep / 6 Oct 2026 | AUKUS / defence | On 6 Oct Anduril and the US Navy announced 'Arsenal-2', a $6.6bn submarine-component yard at Sparrows Point, Maryland ($3.7bn of Anduril's own money plus a Navy contract worth up to $2.9bn), adding ~15% to Virginia-class labour capacity. It is meant to ready production by 2030, starting with torpedo tubes. The aim includes meeting AUKUS sales to Australia in the 2030s. Earlier, after a GAO report on idle US attack subs, Rep. Joe Courtney pointed to Australia's US$8.5bn Henderson (WA) repair investment, and Kurt Campbell warned some at the Pentagon would 'love a stumble' (25 Sep). | AUKUS delivery risk and federal defence spending/fiscal position; WA construction demand; alliance / US-China risk premium | USNI News, 6 Oct 2026 Crikey, 25 Sep 2026 |
| 14 Mar / 13 Apr 2026 | Critical minerals | US-Australia critical minerals framework (signed Oct 2025): at the 14 Mar 2026 Tokyo ministerial, each side said it had provided at least US$1bn of financing within 6 months, with support for 11 named projects (Australia $1.4bn, US $2.2bn) and a new Critical Minerals Supply Security Response Group. China's Oct-2025 rare-earth controls remain suspended under the truce now extended to 10 Jan 2027. | ASX rare-earth/critical-mineral miners; China's rare-earth leverage; foreign capital inflow to the resources sector | DISR (Australian Govt), 13 Apr 2026 |
| 15 Jul 2026 | Iron ore supply (Simandou) | Rio Tinto: SimFer (Simandou) mine construction and port infrastructure more than three-quarters complete; full rail commissioning achieved in Q1 2026. 2026 Simandou sales guidance is 5-10 Mt (100% basis). Pilbara Q2 sales were up 7% y/y. | Medium-term iron ore supply and price (Australia's largest export), Pilbara market share, budget mining receipts | Rio Tinto Q2 2026 production results, 15 Jul 2026 |
Quantitative proxies (context only)
146 +17.8% over 1y
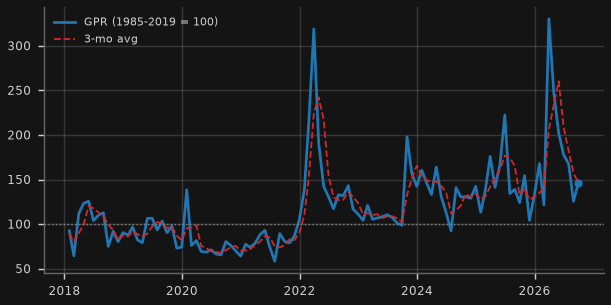
Why it matters for Australia: Spikes in geopolitical risk tend to lift oil and gold and weigh on the AUD and Asian risk assets.
Rule: Context only (no traffic light).
Caveat: Newspaper-text index; levels are relative to the 1985-2019 average (=100). No traffic light by design.
Source: Caldara & Iacoviello GPR index: GPR (monthly)
China 1.12, Taiwan 0.19, Japan 0.28, Korea 0.33, Australia 0.14 +0.2 over 1y
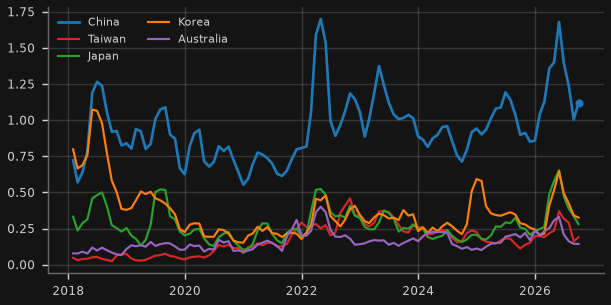
Why it matters for Australia: Shows which Asian flashpoints dominate the risk news flow that markets trade on.
Rule: Context only (no traffic light).
Caveat: Share of newspaper articles mentioning geopolitical risk and the country; latest value field shows China.
Source: Caldara & Iacoviello GPR index: GPRC_CHN, GPRC_TWN, GPRC_JPN, GPRC_KOR, GPRC_AUS
Global 282, US 178, China 239, Japan 97, Korea 395, Australia 244 -33.5% over 1y
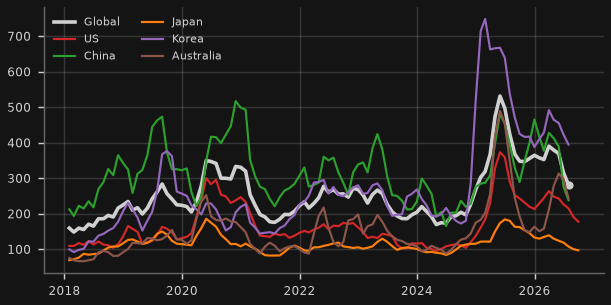
Why it matters for Australia: Policy uncertainty (tariffs, fiscal, elections) delays investment and hiring across the region.
Rule: Context only (no traffic light).
Caveat: Latest value field shows Global (GDP-weighted, current prices). Country indices end on different months (Global Jul 2026, US Sep 2026, China Jul 2026, Japan Sep 2026, Korea Jul 2026, Australia Jul 2026). FRED's China/Japan EPU copies are stale and not used.
Source: Baker, Bloom & Davis EPU (policyuncertainty.com): All_Country_Data.xlsx: GEPU_current, US, China, Japan, Korea, Australia; Japan_Policy_Uncertainty_Data.xlsx; FRED (St Louis Fed): USEPUINDXM
Long-term trends
Context only (no traffic lights): the longest reliable free history for US and Australian yields and GDP. Where no single series covers the period, sources are spliced; every splice is a dotted vertical line on the chart, named in the card caveat,. Grey shading: NBER recessions (US) or named Australian recessions (no official dating).
Bond yields and policy rates
10y 5.22%, 2y 4.75%, FF 3.88% +1.1pp over 1y
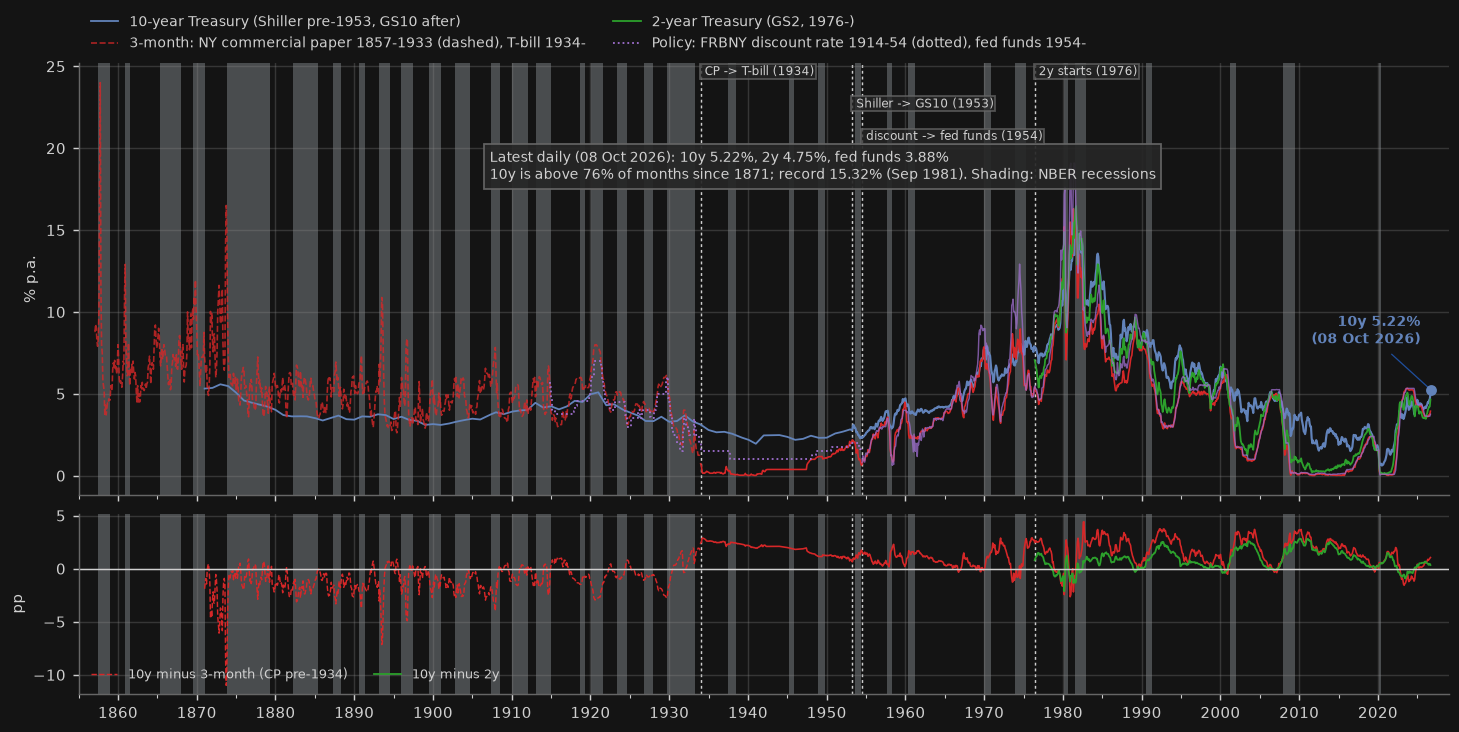
Why it matters for Australia: The US 10-year is the world's benchmark discount rate; long-run context shows whether today's level is unusual or a return to pre-2008 norms, which matters for every leveraged Australian asset priced off global yields.
Rule: Context only (no traffic light).
Caveat: Splices (dotted lines): 10y = Shiller long rate (Homer & Sylla-based; pre-1953 values are annual yields interpolated to monthly, not a constant 10-year maturity) to Mar-1953, then GS10. 3-month = NY commercial paper (NBER) to 1933, then T-bill; commercial paper carries a credit premium (~+0.6pp vs bills in the overlap), so pre-1934 front-end and spread levels are not like-for-like. Policy = FRBNY discount rate to Jun-1954, then fed funds. Chart is monthly; headline uses latest daily values.
Source: Robert Shiller, ie_data.xls (shillerdata.com): Long Interest Rate GS10 (col G), CPI (col E); FRED (St Louis Fed): GS10, DGS10; FRED (St Louis Fed): TB3MS; FRED (St Louis Fed): GS2, DGS2; FRED (St Louis Fed): FEDFUNDS, DFF; FRED (St Louis Fed): M13002US35620M156NNBR; FRED (St Louis Fed): M13009USM156NNBR; FRED (St Louis Fed): USREC
10y 5.40%, 3y 4.93%, cash 4.60% +1.0pp over 1y
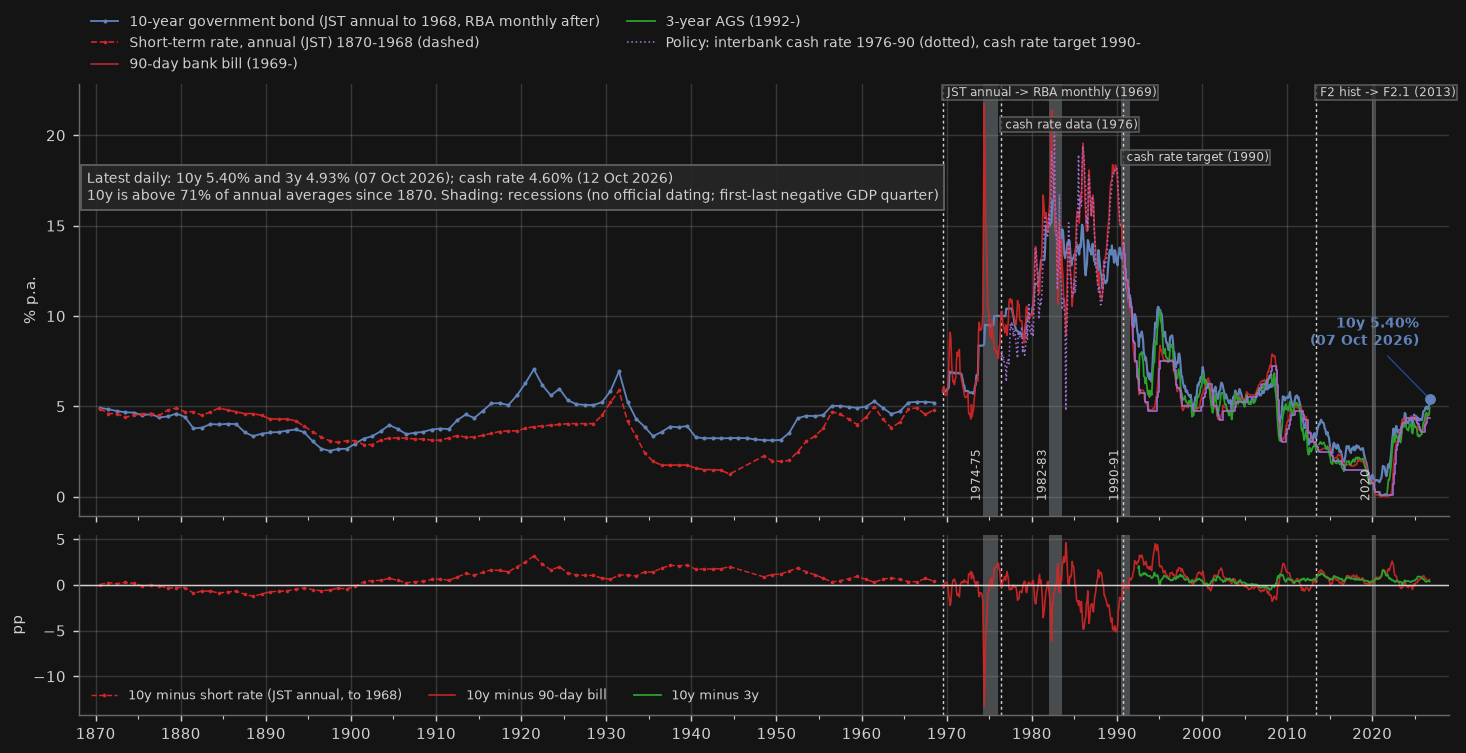
Why it matters for Australia: Australian long rates track US yields plus a premium; the long history shows where today's 10y sits against the high-inflation 1970s-80s and the near-zero 2010s.
Rule: Context only (no traffic light).
Caveat: Splices (dotted lines): 10y = JST annual long-term government bond yield 1870-1968 (not a constant 10-year maturity), then RBA monthly 10-year (F2 historical to Apr-2013, F2.1 from May-2013). Front end = JST annual short-term rate to 1968, then 90-day bank bills (different instruments; see README splice table). Recession shading: 1974-75 = Apr 1974-Dec 1975; 1982-83 = Jan 1982-Jun 1983; 1990-91 = Jul 1990-Jun 1991; 2020 = Jan 2020-Jun 2020 (first to last negative quarter of real GDP within each named period; Australia has no official recession dating).
Source: Jorda-Schularick-Taylor Macrohistory Database R6: ltrate, stir, gdp, rgdpmad x pop, cpi; RBA historical table f02histhist: FCMYGBAG10, FCMYGBAG3; RBA table F2.1: FCMYGBAG10, FCMYGBAG3; RBA table F2: FCMYGBAG10D, FCMYGBAG3D; RBA table F1.1: FIRMMBAB90, FIRMMCRI, FIRMMCRT; RBA table F1: FIRMMCRTD; RBA table H1: GGDPCVGDP (recession shading)
Output (GDP)
real +2.2% y/y, nominal +6.3% -0.2pp over 1y
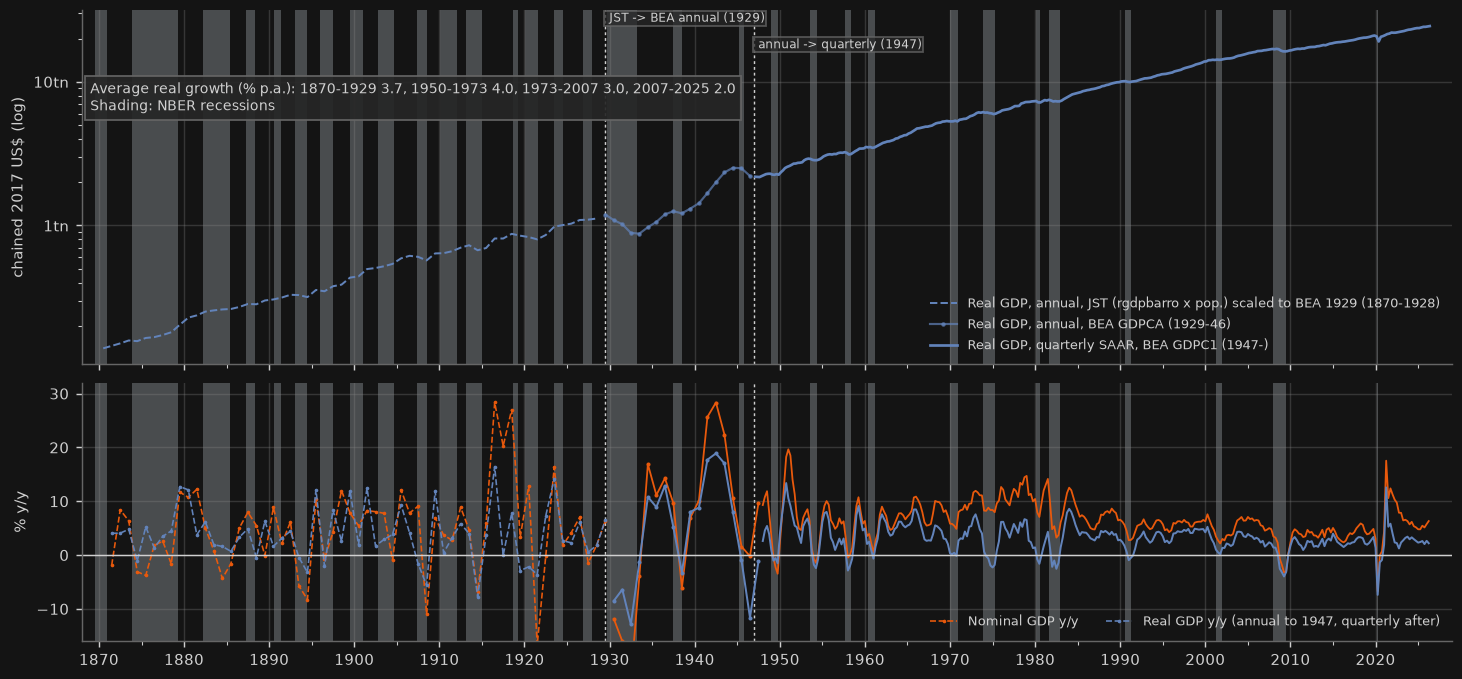
Why it matters for Australia: US nominal growth sets the 'natural' level for long yields and the income that services US debt; the long record shows how unusual (or not) the current expansion is.
Rule: Context only (no traffic light).
Caveat: Splices (dotted lines): pre-1929 real GDP = JST real GDP per capita x population (measure chosen by best fit to BEA; see README) ratio-linked to BEA at 1929; 1929-46 BEA annual; quarterly BEA from 1947. Pre-1929 estimates are reconstructions (Maddison/Balke-Gordon type) with wide error bands. Annual growth plotted mid-year.
Source: Jorda-Schularick-Taylor Macrohistory Database R6: ltrate, stir, gdp, rgdpmad x pop, cpi; FRED (St Louis Fed): GDPC1, GDP; FRED (St Louis Fed): GDPCA, GDPA; FRED (St Louis Fed): USREC
real +2.1% y/y, nominal +5.3% +0.2pp over 1y
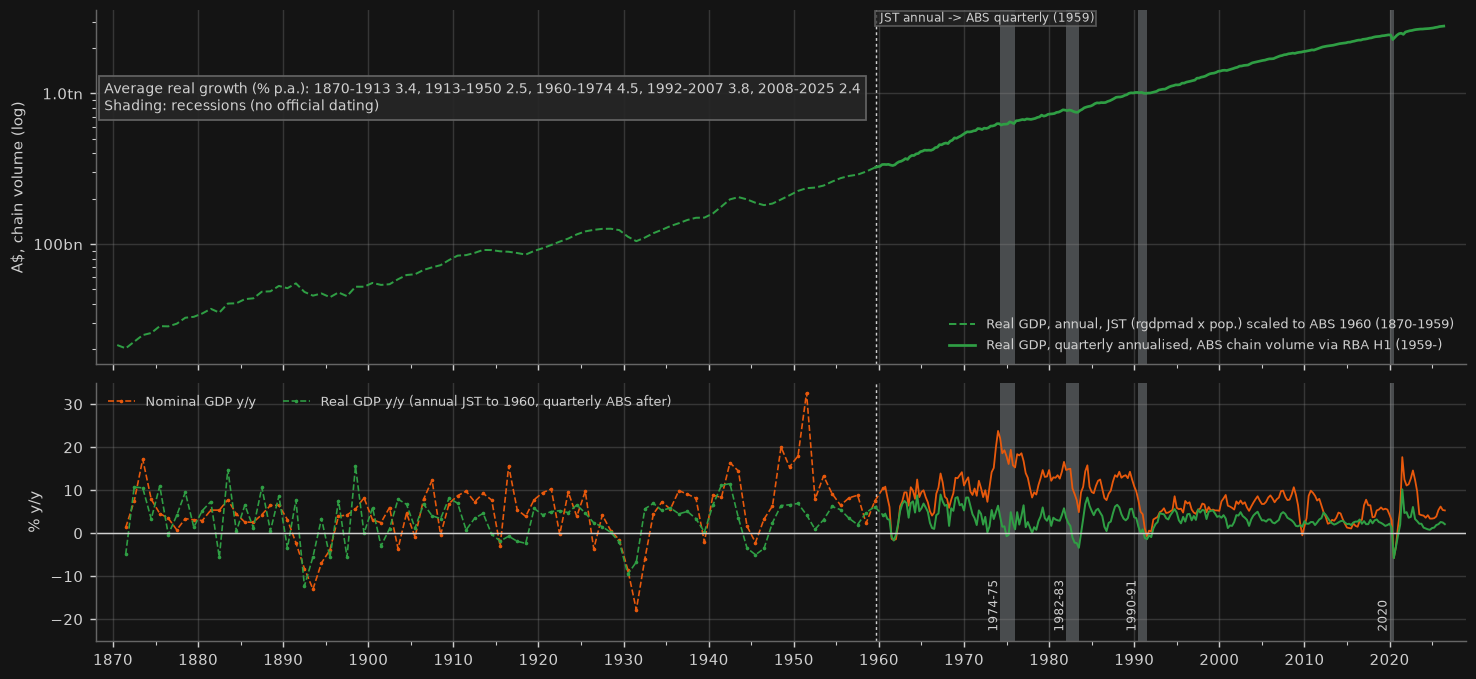
Why it matters for Australia: Nominal GDP growth is the income stream that services Australia's household and business debt; when it runs below borrowing rates, leverage starts to bite.
Rule: Context only (no traffic light).
Caveat: Splice (dotted line): JST annual real GDP (per capita x population) 1870-1959 ratio-linked to ABS chain-volume GDP (RBA H1) at 1960; quarterly ABS from Sep-1959. Pre-1959 Australian GDP is a historical reconstruction (Butlin/Haig-based, via Maddison) with wide error bands. JST data end in 2020; they are only used before 1960.
Source: Jorda-Schularick-Taylor Macrohistory Database R6: ltrate, stir, gdp, rgdpmad x pop, cpi; RBA table H1: GGDPCVGDP, GGDPCVGDPY, GGDPECCPGDP, GGDPECCPGDPY
Now vs 1983-2007 trend: US -22%, Australia -19% breaks US 1880, 1899, 1932, 1946, 1965, 2009 | AU 1892, 1903, 1915, 1930, 1945, 1969, 1999
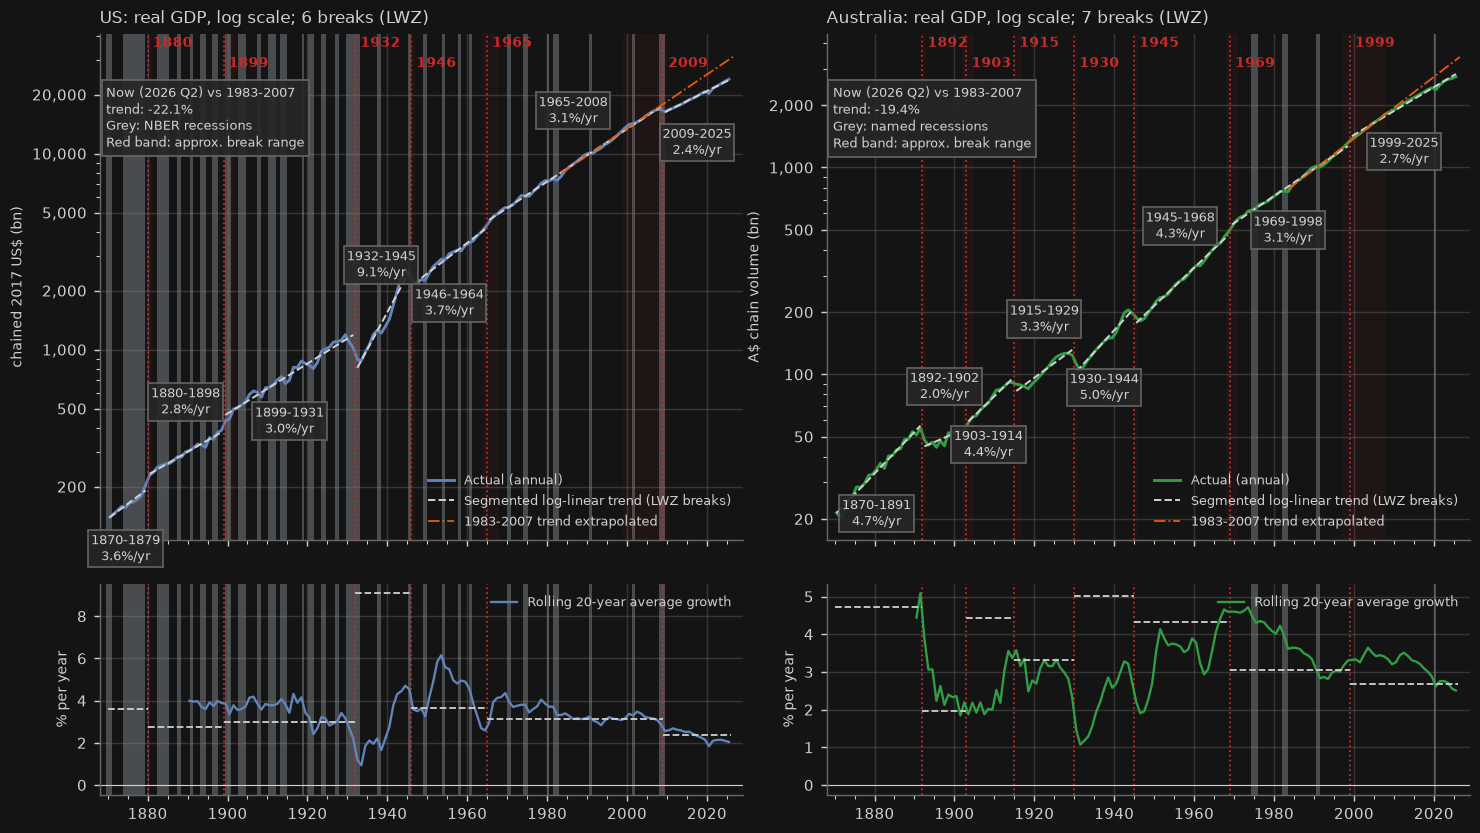
Why it matters for Australia: Separates temporary slumps (level returns to the old trend) from permanent losses; a lower trend after 2008 means less income growth to carry debt at today's real rates.
Rule: Context only (no traffic light).
Caveat: Bai-Perron-style least-squares breaks in a log-linear trend (each segment has its own level and slope), minimum segment 10 years, number of breaks by the LWZ criterion (BIC picks as many or more). Break-year bands are approximate (profile likelihood; ignore serial correlation, so true uncertainty is wider). Pre-1950 data are annual historical reconstructions (JST/Maddison) with large error bands, spliced to BEA (1929) and ABS (1960); Australian population from JST to 1959 ratio-linked to World Bank from 1960. The US 1880 break reflects 12% growth in both 1879 and 1880 in the historical reconstructions (resumption boom), which are uncertain. Full tables: data/gdp_trend_segments.csv and data/gdp_shock_recovery.csv.
Source: Jorda-Schularick-Taylor Macrohistory Database R6: ltrate, stir, gdp, rgdpmad x pop, cpi; FRED (St Louis Fed): GDPCA, GDPC1, B230RC0A052NBEA, POPTOTAUA647NWDB, USREC; RBA table H1: GGDPCVGDP
Now vs 1983-2007 trend: US -15%, Australia -24% breaks US 1880, 1899, 1932, 1946, 2009 | AU 1892, 1915, 1930, 1945, 2004
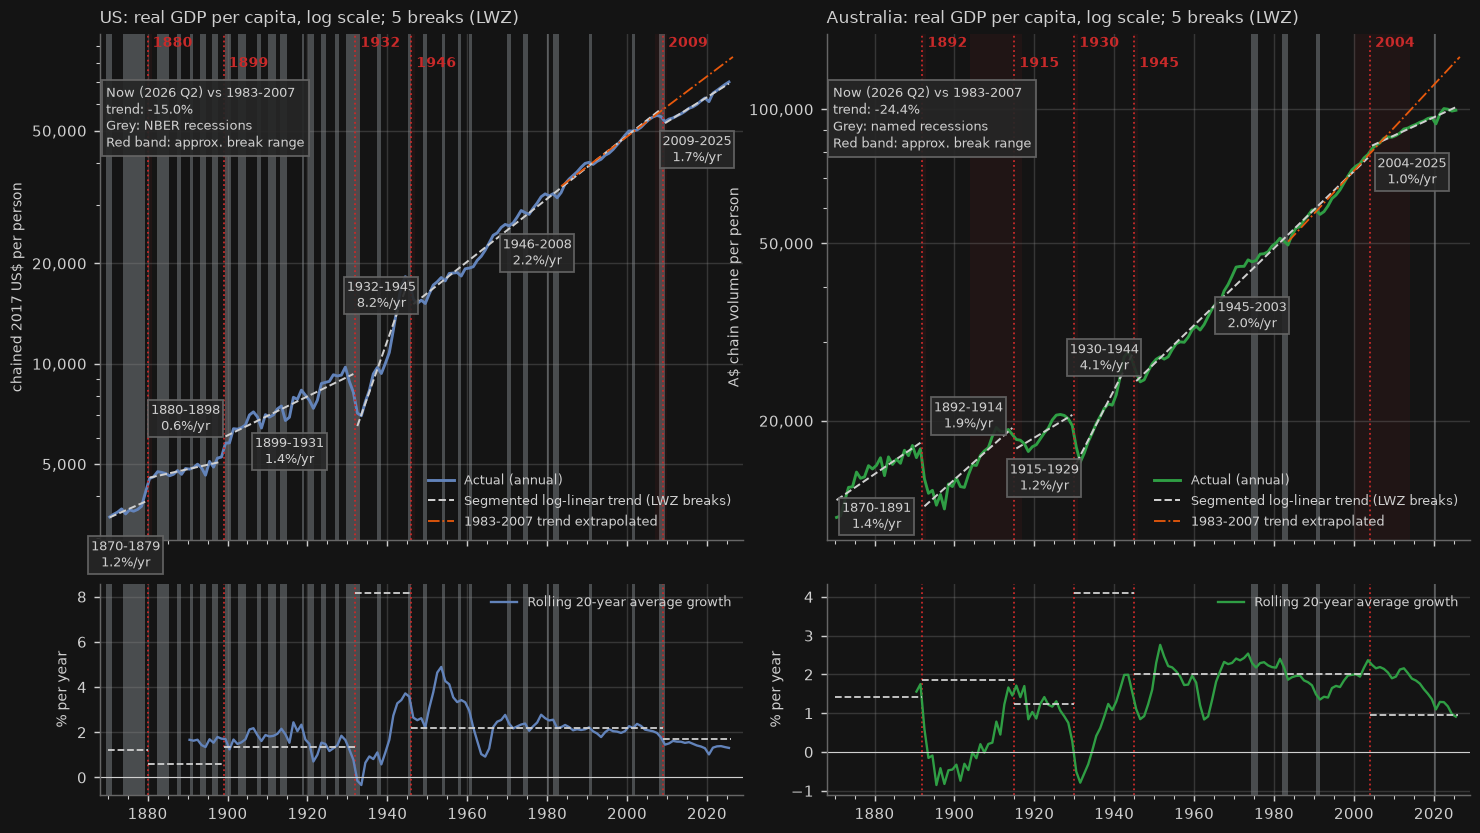
Why it matters for Australia: Separates temporary slumps (level returns to the old trend) from permanent losses; a lower trend after 2008 means less income growth to carry debt at today's real rates.
Rule: Context only (no traffic light).
Caveat: Bai-Perron-style least-squares breaks in a log-linear trend (each segment has its own level and slope), minimum segment 10 years, number of breaks by the LWZ criterion (BIC picks as many or more). Break-year bands are approximate (profile likelihood; ignore serial correlation, so true uncertainty is wider). Pre-1950 data are annual historical reconstructions (JST/Maddison) with large error bands, spliced to BEA (1929) and ABS (1960); Australian population from JST to 1959 ratio-linked to World Bank from 1960. The US 1880 break reflects 12% growth in both 1879 and 1880 in the historical reconstructions (resumption boom), which are uncertain. Full tables: data/gdp_trend_segments.csv and data/gdp_shock_recovery.csv.
Source: Jorda-Schularick-Taylor Macrohistory Database R6: ltrate, stir, gdp, rgdpmad x pop, cpi; FRED (St Louis Fed): GDPCA, GDPC1, B230RC0A052NBEA, POPTOTAUA647NWDB, USREC; RBA table H1: GGDPCVGDP
Yields vs growth and real yields
US -1.9pp, Australia -0.4pp -1.5pp over 1y
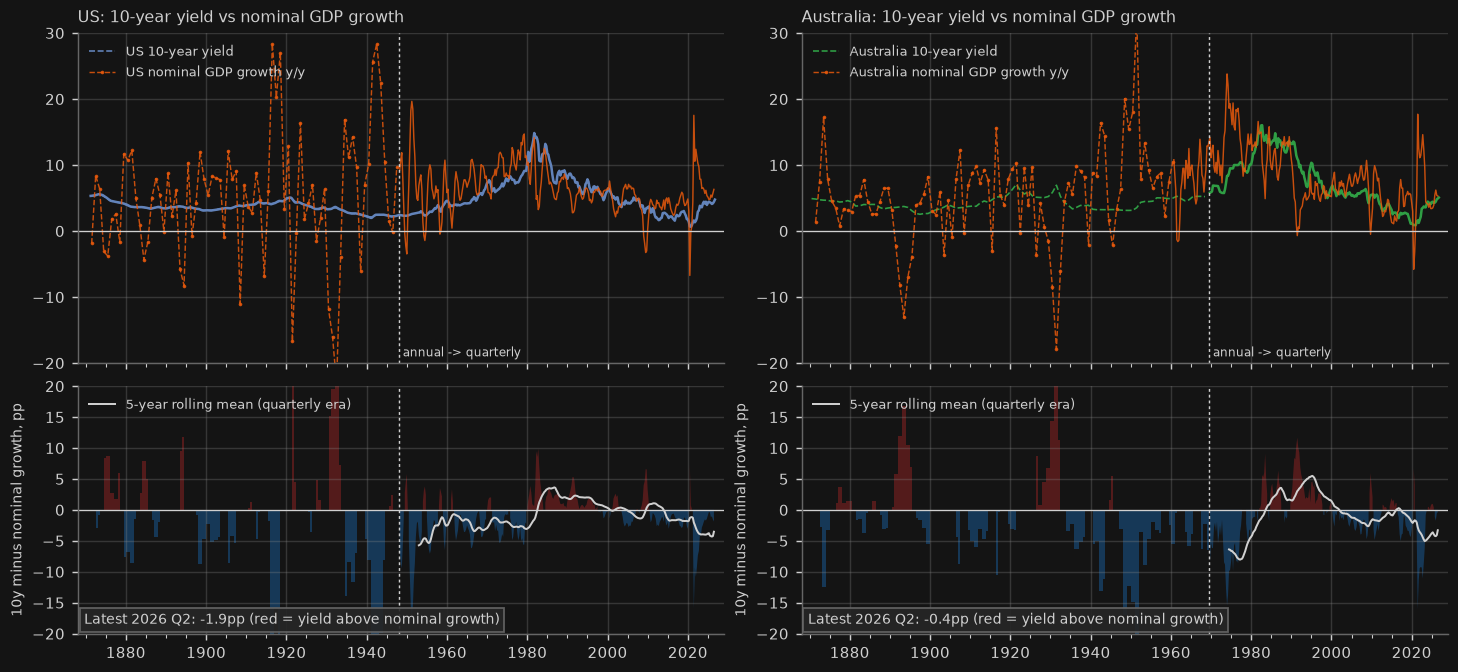
Why it matters for Australia: The thesis test in one chart: when the 10-year yield runs above nominal GDP growth, debt grows faster than the income that services it and leveraged assets come under pressure.
Rule: Context only (no traffic light).
Caveat: Gap = 10-year yield minus year-ended nominal GDP growth (annual before 1948 US / 1969 Australia; quarterly after). Uses quarter-average monthly yields, so it lags the latest daily yields. Year-ended growth swings sharply in shocks (2020-21); the 5-year mean shows the regime.
Source: Robert Shiller, ie_data.xls (shillerdata.com): Long Interest Rate GS10 (col G), CPI (col E); FRED (St Louis Fed): GS10, GDP, GDPA; Jorda-Schularick-Taylor Macrohistory Database R6: ltrate, stir, gdp, rgdpmad x pop, cpi; RBA table F2.1: FCMYGBAG10; RBA table H1: GGDPECCPGDPY
US +1.5pp, Australia +1.5pp -0.4pp over 1y
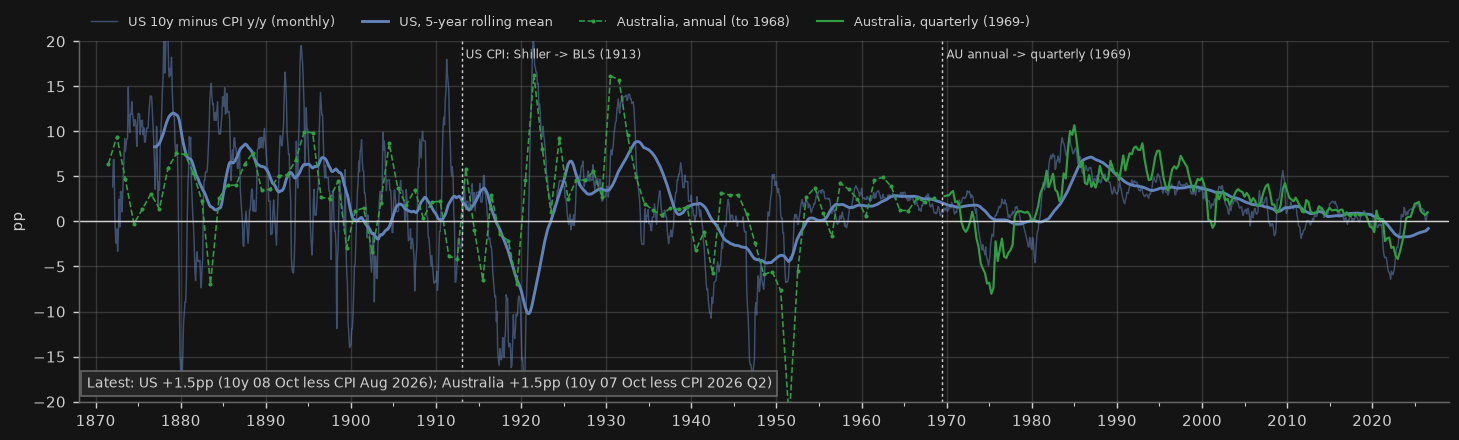
Why it matters for Australia: Your thesis variable over 150 years: sustained positive real long rates (1920s-30s, 1980s-90s) coincided with deleveraging; deeply negative ones (1940s, 1970s, 2021-22) eroded debt.
Rule: Context only (no traffic light).
Caveat: Realised (backward-looking) inflation, not expected inflation; for market real yields since 1997/1986 see the TIPS and indexed-bond cards. Australian CPI includes the 2000 GST step. Splices marked by dotted lines.
Source: Robert Shiller, ie_data.xls (shillerdata.com): Long Interest Rate GS10 (col G), CPI (col E); FRED (St Louis Fed): GS10, DGS10, CPIAUCNS; Jorda-Schularick-Taylor Macrohistory Database R6: ltrate, stir, gdp, rgdpmad x pop, cpi; RBA table F2.1: FCMYGBAG10; RBA table G1: GCPIAGYP
Productivity (Australia)
GDP/hour -0.1% vs Dec-19 (-8.8% vs trend); market sector +2.8% -0.2% over 1y
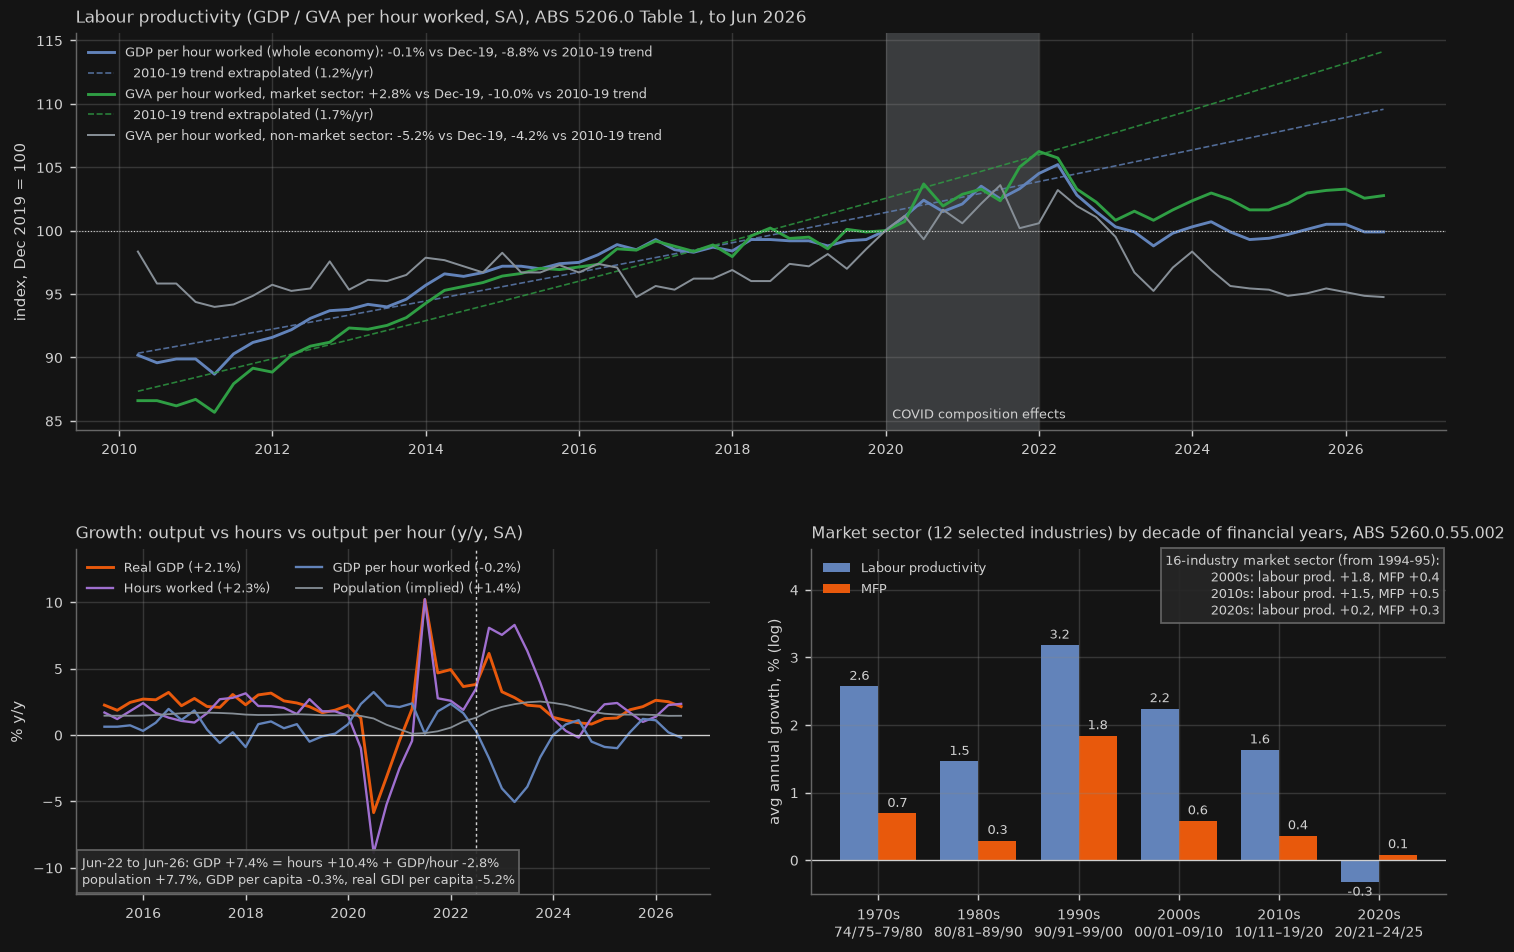
Why it matters for Australia: Productivity is the only lasting source of per-capita income growth; when it stalls, higher real rates have to be serviced from flat real incomes.
Rule: Context only (no traffic light).
Caveat: Non-market sector output (health, education, public administration, much of the care economy incl. NDIS) is largely measured by inputs, so its measured productivity is near flat by construction; the shift of hours into these sectors drags whole-economy GDP/hour. 2020-21 levels are inflated by composition (low-paid, low-output hours dropped out in lockdowns), so the post-2021 fall partly unwinds that. MFP data are annual to 2024-25 (released Feb 2026); the 2020s bar covers only 5 years. Implied population = GDP / GDP per capita.
Source: ABS 5206.0 Table 1 (Key aggregates): A2304192L GDP/hour, A3606058X & A130272211T GVA/hour market & non-market, A2304428W hours, A2304402X GDP, A2304404C GDP per capita, A2304410X real GDI (SA); ABS 5260.0.55.002 Industry multifactor productivity: Tables 2-5 (market sector, 12 selected industries); ABS 6345.0 Wage Price Index Table 1: A2713849C (all sectors, SA); RBA table G1: GCPIAG
About / sources. A rules-based monitor of the Australian macro and credit cycle from an Asian and US-funding perspective. All data are free public sources: RBA, ABS, BIS, OECD, FRED (St Louis Fed), Federal Reserve Board (H.4.1, GSW yield curve), NY Fed Markets API (reference rates, primary dealer statistics), Japan Ministry of Finance, China NBS releases, ASIC, World Bank Pink Sheet, Geopolitical Risk / EPU indices, Yahoo Finance (unofficial chart endpoint). Each card names its series IDs and links to the source; release lags differ by series. Machine-readable latest values: data/latest_summary.csv.
Disclaimer: for information and education only; not financial, investment or tax advice. Data may be revised, delayed or contain errors; check the original source before relying on any figure.